


Finding Mortgage Brokers in Cornwall is not simply about choosing the adviser closest to your postcode.
Cornwall’s property market stretches from Truro and larger towns such as St Austell to fishing communities, rural villages and some of Britain’s most recognisable coastal locations. Property type, intended use, income structure and location can all influence how lenders assess a mortgage application.
Cornwall Property Market and Mortgage Considerations
Cornwall’s average house price was £276,000 in July 2026, according to the Office for National Statistics.
First-time buyers paid an average of £227,000, while homes bought with a mortgage averaged £268,000. These are county-wide averages and should not be treated as a valuation for an individual town or property.
View the latest ONS housing data for Cornwall.
The county average also hides substantial local differences.
Connect Experts helps you find a mortgage adviser by location, mortgage experience and personal preferences.
Whether you are buying your first home, moving to Cornwall, remortgaging, or buying an investment property, the goal is to find an adviser whose experience matches the mortgage you actually need.
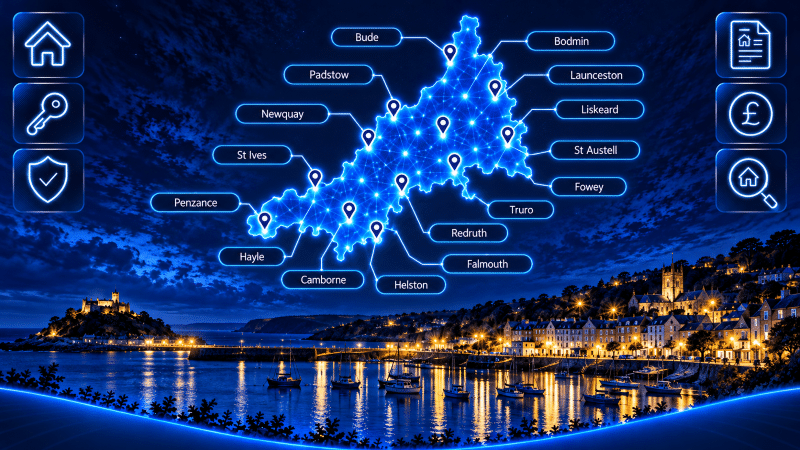
Mortgage Advice Across Cornwall
Two homes in Cornwall can carry the same asking price yet create very different mortgage considerations.
A modern house in Truro may present a relatively conventional lending case. A granite cottage, coastal apartment, rural smallholding or property intended for holiday letting may require additional lender assessment.
A mortgage adviser may help you understand issues involving:
- mortgage affordability;
- first-time buyer mortgages;
- moving home;
- remortgaging;
- self-employed and variable income;
- buy-to-let mortgages;
- holiday let finance;
- limited company borrowing;
- previous credit problems;
- unusual or non-standard property;
- larger mortgage requirements.
Cornwall’s existing page already identifies coastal property, rural access, non-standard construction and holiday letting as recurring local lending considerations.
If discussing your mortgage in another language would make the process clearer, you can also explore Bilingual Mortgage Brokers.
Moving to Cornwall can involve more than changing address.
For some households, the move may also mean changing jobs, working remotely, becoming self-employed, or running a tourism- and hospitality-related business.
The existing Cornwall page reflects the county’s mix of tourism, healthcare, agriculture and self-employed work.
That matters because lenders assess where income comes from and whether it can be demonstrated reliably.
A mortgage application may therefore need to consider:
- employed income;
- self-employed profits;
- company director income;
- seasonal earnings;
- bonuses or commission;
- multiple income sources;
- deposit size;
- outstanding commitments;
- property type;
- intended property use.
The location may inspire the move, but affordability still determines how the mortgage is assessed.
How to Choose a Mortgage Broker in Cornwall
Local knowledge can be useful, but location should not be the only criterion.
The more important question is whether the adviser has experience suited to your circumstances.
Before choosing a broker, consider asking:
- Do you advise regularly on mortgages like mine?
- Have you worked with this type of property?
- How do you assess self-employed or variable income?
- Can you advise on holiday lets if that is my intended use?
- What range of lenders can you consider?
- What fees may apply?
- How will you communicate during underwriting?
- Can advice be provided remotely if required?
You can check the relevant firm and permissions using the FCA Financial Services Register.
Connect Experts is a directory and matching platform. Mortgage advice is provided by the adviser or firm you choose.
Start Your Search for a Mortgage Broker in Cornwall
A useful adviser search should consider your wider financial circumstances as well as the property.
Education
Cornwall provides state and independent education across the county, while some families may also consider schools in neighbouring Devon or boarding options further afield.
Where private education forms part of household planning, school fees can affect disposable income and longer-term mortgage affordability.
Families exploring how education costs could be funded can read more about Education Finance.
Consider education finance separately from the mortgage, but both commitments may be part of wider household planning.
Finance
Mortgage affordability is rarely based on salary alone.
Lenders can consider:
- household income;
- deposit;
- outstanding borrowing;
- credit commitments;
- childcare;
- property type;
- mortgage term;
- loan-to-value;
- other regular expenditure.
Applicants with self-employment, seasonal work, or multiple income streams may need lenders that assess earnings differently from a straightforward monthly salary.
Understanding this early can make the adviser search more efficient.
Holiday Lets and Buy-to-Let in Cornwall
Cornwall’s tourism economy makes the intended use of a property particularly important.
A property purchased as a permanent home, a conventional buy-to-let, or a furnished holiday let may each fall under different lender criteria.
Lenders can consider factors such as:
- expected rental income;
- seasonal demand;
- minimum income requirements;
- property location;
- occupancy restrictions;
- personal or limited company ownership;
- deposit requirements;
- whether personal use is permitted.
A property may attract visitors but still not suit every holiday-let lender.
Users considering an investment property should therefore look for an adviser whose permissions and experience match the proposed borrowing structure.
Mortgage Protection and Longer-Term Planning
A mortgage can remain in place for decades.
Protection planning may therefore be part of the wider discussion about how a household would manage its commitments after death, serious illness, or an unexpected change in income.
The type of protection required depends on personal circumstances, existing benefits, mortgage size, family responsibilities and budget.
Consider it on its own merits rather than as an automatic part of taking a mortgage.
For more information, read our Holiday Let Guide
Later-Life Property Decisions in Cornwall
Cornwall is also popular with older homeowners and people considering retirement moves.
Later-life financial decisions may include:
- moving to a smaller home;
- remortgaging;
- clearing an existing mortgage;
- helping family members financially;
- adapting a property;
- considering equity release.
Equity release is different from a conventional residential mortgage and requires specialist advice.
Users considering this route can explore Equity Release Advisers in Cornwall.
Specialist Mortgage Considerations in Cornwall
High-Net-Worth
Cornwall is not uniformly a high-net-worth market.
However, locations such as Rock, Padstow, St Mawes and parts of St Ives can include significantly higher-value homes and buyers with more complex financial circumstances.
Larger mortgage requirements can involve:
- investment income;
- company profits;
- bonuses;
- significant assets;
- multiple properties;
- complex income structures;
- larger deposits;
- bespoke underwriting.
Where these circumstances apply, High Net Worth Mortgage Brokers can help users identify advisers with relevant experience.
Higher-value borrowing may also increase the need to consider how family finances and liabilities would be protected. Read more through High Net Worth Protection Services.
People Also Browse these Counties
If you are Looking for a Mortgage Network
“Hi, I’m Liz Syms, Chief Executive Officer and founder of Connect Experts, Connect Mortgages, and Connect for Intermediaries.
If you are a UK mortgage broker based in Cornwall, joining our mortgage network can help you increase your visibility to clients actively searching for trusted, FCA-authorised advice. Brokers featured on our Cornwall mortgage brokers page are matched with clients who value clear communication and professional guidance, including those who prefer advice in a specific language.
Our platform is designed to support compliant, client-focused advisers and help you connect with the right audience across Cornwall.”
Choose the option that suits you best:
Option 1: Schedule a call with our Business Recruitment Manager
Option 2: Complete our contact form
Option 3: Call us

Connect Experts is a mortgage adviser directory and matching platform. We help users find FCA-authorised mortgage advisers. We are not a lender, and the adviser you choose will provide advice based on your circumstances.
Important:
Your home may be repossessed if you do not keep up repayments on your mortgage or any loan secured on it. Some forms of buy-to-let, commercial mortgage and business finance may not be regulated by the Financial Conduct Authority.