
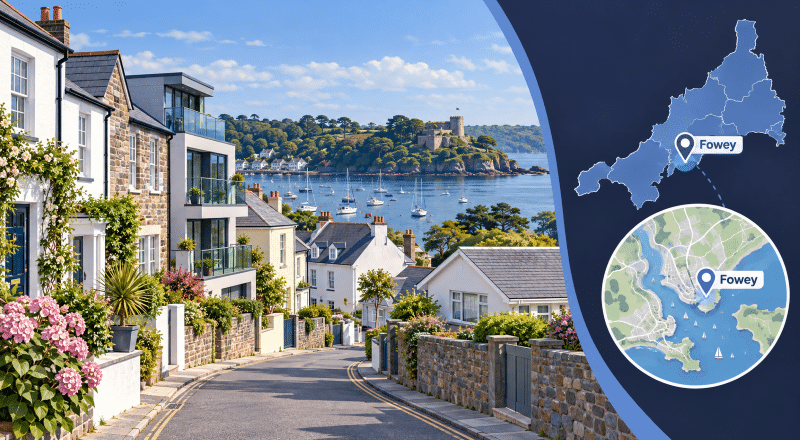
A Mortgage Broker in Fowey can help you consider more than the mortgage rate when planning your next move.
Fowey’s property market is shaped by its harbour, historic streets, coastal setting, and varied housing stock. These characteristics can make property choice a key part of mortgage planning.
The right mortgage should support what comes next, not just make today’s purchase possible.
A mortgage adviser can review your income, deposit, property and future plans before discussing suitable lender options.
Connect Experts helps you search for mortgage advisers by location, experience, language and other preferences.
At a glance: Mortgage Broker in Fowey
- Fowey sits on Cornwall’s south coast within the PL23 postcode area.
- PL23 recorded an average sold price of around £531,000 over the latest year.
- Cornwall’s average house price was approximately £276,000 in July 2026.
- Fowey includes historic homes, terraces, apartments and larger detached properties.
- Individual Fowey homes have recently sold for more than £1 million.
- Property age, construction, condition and title can affect lender assessment.
- High-value borrowing may require more detailed underwriting.
- Protection should form part of wider mortgage planning where appropriate.
- Adviser experience may matter more than physical distance.
The Office for National Statistics and HM Land Registry reported an average Cornwall house price of approximately £276,000 in July 2026.
However, Fowey should not be judged only against the county average.
Recent PL23 transaction data shows an annual average of around £531,000. Individual areas and properties can vary considerably.
Why Fowey Can Require a More Careful Mortgage Search
Choosing where to live often begins with lifestyle.
Financing that home requires a different set of questions.
A Mortgage Broker in Fowey may review both your personal circumstances and the property being purchased.
Lenders can consider factors including:
- purchase price;
- deposit;
- employment and income;
- existing financial commitments;
- credit history;
- property construction;
- property condition;
- lease terms, where relevant;
- intended use of the property;
- valuation;
- affordability.
Historic or unusual homes may also require closer examination by the lender or valuer.
Cornwall Council explains that conservation areas protect locations with particular architectural or historic importance. Planning considerations can therefore differ within historic environments.
Fowey also has its own neighbourhood development plan, which Cornwall Council records as adopted in March 2020.
These planning matters do not decide whether you can obtain a mortgage. However, they demonstrate why local property characteristics should not be ignored.
What Can a Mortgage Broker in Fowey Help With?
Mortgage advice should start with your circumstances, not a particular lender.
An adviser may help you examine:
- how much you could realistically borrow;
- how lenders assess your income;
- the deposit you may need;
- fixed, tracker and other mortgage options;
- mortgage fees;
- affordability;
- lender criteria;
- property-related lending restrictions;
- likely documentation;
- potential monthly repayments.
They can then consider lenders whose criteria appear appropriate for your situation.
This can be especially useful when income or property circumstances fall outside standard lending patterns.
First-Time Buyers in Fowey
Buying your first home can involve decisions you haven’t needed to make before.
Your deposit is only one consideration.
Lenders may also review your income, regular commitments, credit history, and the property itself.
A first-time buyer adviser can explain the process before you begin making firm commitments.
You can search Connect Experts for First-Time Buyer Mortgage Advisers with relevant experience.
An Agreement in Principle may also help establish an indicative borrowing range. It does not guarantee a later mortgage offer.
Moving Home in Fowey
Moving home involves two financial decisions happening together.
You may be selling one property while arranging finance for another.
An adviser can help you consider:
- your existing mortgage balance;
- equity from your current property;
- early repayment charges;
- whether your mortgage may be portable;
- additional borrowing;
- affordability;
- deposit requirements;
- alternative lender options.
Our Moving Home Mortgage Guide explains several of these considerations.
Good planning matters most when a sale and purchase depend on each other.
When Your Current Mortgage Rate Is Ending
When a mortgage deal ends, it’s a natural time to reconsider your borrowing.
Doing nothing may mean moving onto your lender’s standard variable rate.
However, switching lenders isn’t automatically the right answer.
A review can compare a product transfer with remortgage options and consider fees alongside the headline rate.
Connect Experts can help you search for Mortgage Rate Ending Advisers before your existing arrangement expires.
The best decision is usually based on overall cost and your future plans.
High-Value Mortgages in Fowey
Fowey deserves separate consideration for higher-value borrowing.
PL23 recorded average sold prices of approximately £531,000 during the latest year. Detached properties averaged considerably more.
Recent Fowey transactions also show considerable variation in the local market.
For example, a property on Daglands Road sold for £1.3 million in 2026.
Current asking prices should never be treated as evidence of completed market values. However, Fowey also contains homes marketed well above £1 million.
Higher property values do not automatically make someone a high-net-worth mortgage customer.
However, larger loans or complex financial circumstances may require advisers experienced with:
- substantial mortgage balances;
- business ownership;
- retained company profits;
- bonuses;
- investment income;
- multiple income sources;
- overseas income;
- interest-only borrowing;
- complex repayment strategies;
- specialist or private bank lending.
Clients with these circumstances can search for High Net Worth Mortgage Brokers through Connect Experts.
The right lender may be mainstream, specialist or private banking. The right route depends on the full financial picture.
Self-Employed and Complex Income
A strong income does not always fit neatly into a lender’s standard application process.
Self-employed applicants may need to provide accounts, tax calculations and tax-year overviews.
Company directors may receive salary, dividends or other income.
Contractors may face different evidence requirements.
A mortgage adviser can examine how different lenders assess legitimate income structures before an application is submitted.
This can reduce the risk of approaching a lender whose criteria do not fit the case.
Protection Alongside Your Mortgage
A mortgage creates a long-term financial commitment.
Therefore, arranging the borrowing is only part of the conversation.
Clients may also want to consider what could happen to household finances following death, serious illness or an extended period away from work.
Protection needs vary between households.
Suitable advice could include discussions around:
- life insurance;
- critical illness cover;
- income protection;
- family circumstances;
- existing workplace benefits;
- mortgage commitments.
You can search for Protection Mortgage Brokers through Connect Experts.
Protection advice should reflect your circumstances, existing cover, and budget, not just the size of the mortgage.
Equity Release Advice in Cornwall
Later-life homeowners can face a very different financial decision.
Some may have substantial value within their home but want to understand whether accessing part of that equity is appropriate.
Equity release may include lifetime mortgages or home reversion plans.
It is not suitable for everyone.
Among other factors, advice should consider:
- age;
- property value;
- existing borrowing;
- future plans;
- inheritance wishes;
- alternative options;
- potential effects on means-tested benefits.
Homeowners looking specifically for later-life advice can visit Equity Release Advisers in Cornwall on the Connect Lifetime Mortgages website.
Equity release will reduce the value of your estate and may affect your entitlement to means-tested benefits.
Property Type Can Matter in Fowey
A mortgage application assesses both borrower and property.
This matters in areas with diverse housing.
Depending on the home, lenders or valuers may consider:
- construction type;
- structural condition;
- listed status;
- lease length;
- service charges;
- access;
- title restrictions;
- previous alterations;
- commercial use nearby;
- intended occupancy.
A valuation is also undertaken for the lender’s purposes.
It should not automatically be treated as a detailed structural survey.
Buyers may therefore choose an appropriate independent survey based on the property’s age and condition.
Choosing a Mortgage Broker in Fowey
The nearest adviser is not automatically the most suitable adviser.
What matters is whether they understand your circumstances and have suitable experience.
Before choosing someone, consider asking:
- Does the adviser regularly handle cases like mine?
- Which mortgage areas can they advise on?
- How will meetings take place?
- Which lenders can they access?
- What fees could I pay?
- How are those fees calculated?
- How will they communicate during the application?
- What information should I prepare?
A good mortgage conversation should leave you clearer about the decision.
It should not simply leave you with another product to consider.
Search for Mortgage Advice in Fowey
Finding the right home and arranging the right mortgage are connected decisions, but they are not the same decision.
A Mortgage Broker in Fowey can assess your borrowing needs, property and financial circumstances before discussing suitable options.
Connect Experts lets you compare adviser profiles and search by the expertise that matters to you.
You can also search by location, language and adviser preference.
The objective is not simply to find an available adviser.
It is to find someone whose experience fits the question you are trying to answer.




