Mortgage Broker in Philiphaugh searches often start with a property, but the more important question is whether the mortgage fits the life you’re building around it.
A home can look straightforward from the road while presenting a very different picture to a lender. Around Philiphaugh and western Selkirk, that might mean traditional construction, proximity to rivers and flood-management areas, a rural plot, additional land, outbuildings, or simply a property that doesn’t fit neatly into a standard suburban lending model.
Good mortgage advice therefore starts before the application.
It starts with understanding the borrower, the property, and what a lender is likely to see when the two come together.
At a glance: Mortgage Broker in Philiphaugh
- Philiphaugh sits on the western side of Selkirk within the TD7 postcode area.
- The area combines established housing around Selkirk with countryside, farmland, woodland and estate property.
- The Ettrick Water and local flood-management history may make flood information relevant to some properties.
- The historic Battle of Philiphaugh means parts of the surrounding landscape have recognised archaeological and heritage importance.
- The average Scottish Borders home cost approximately £195,000 in August 2026.
- First-time buyers in the Scottish Borders paid approximately £150,000 on average during the same month.
- Mortgage buyers paid approximately £202,000 on average across the Scottish Borders.
- Construction, land, access, property use and location can matter as much as the asking price.
- Consider protection alongside the mortgage rather than after completion.
- Specialist mortgage experience can sometimes matter more than being physically closest to the property.
The latest local figures are provisional and can change as further transactions are recorded.
Mortgage Advice Around Philiphaugh and Selkirk
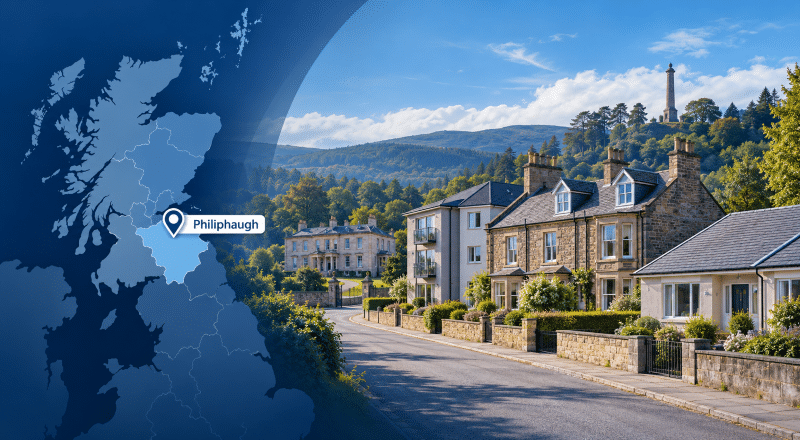
Philiphaugh lies immediately west of Selkirk, where the town meets the wider Ettrick and Yarrow landscape.
That transition matters.
A conventional home on established residential streets may meet mainstream lender criteria without raising unusual questions. However, move toward the edge of the settlement, and property characteristics can become more varied.
Buyers may encounter:
- traditional stone construction;
- detached homes on larger plots;
- cottages;
- former agricultural buildings;
- houses beside open countryside;
- properties with garages or substantial outbuildings;
- private access arrangements;
- homes close to watercourses;
- mixed residential and business use; and
- properties accompanied by additional land.
None of these automatically creates a mortgage problem.
They simply make accurate information more important.
A Mortgage Broker in Philiphaugh can look beyond the mortgage rate and consider whether the property and your circumstances fit the chosen lender’s criteria before an application is submitted.
That can be particularly valuable where a property is difficult to describe using only a postcode, number of bedrooms and purchase price.
Why Philiphaugh Properties Can Need a Closer Look
A lender isn’t buying the home with you.
It assesses whether the property provides acceptable security for the money being borrowed.
That distinction explains why two buyers with similar incomes and deposits can receive very different outcomes when purchasing different homes.
Traditional and older buildings
Selkirk has a long architectural history.
The town’s conservation area contains a mix of building styles and traditional materials, including sandstone, whinstone, render, and slate. Scottish Borders Council also identifies numerous listed properties within the conservation area.
Philiphaugh itself sits outside much of the historic town centre, but buyers moving around the wider Selkirk area can encounter properties whose age, alterations or construction require closer assessment.
A lender may consider:
- construction type;
- roof covering;
- structural condition;
- evidence of significant alterations;
- valuation comments;
- remaining useful life;
- marketability; and
- whether specialist reports are required.
An attractive old building and acceptable mortgage security are related questions, but they are not the same question.
Land and outbuildings
The countryside begins quickly west of Selkirk.
Where a property includes several acres, grazing, substantial workshops, barns or other outbuildings, an adviser should establish exactly what is included in the title and how every part will be used.
Some lenders are comfortable with modest additional land.
Others limit acreage or become cautious when the property appears predominantly agricultural, commercial, or capable of being divided into several uses.
Describe the whole property at the beginning.
Finding the right lender for the real property is usually better than explaining important details after a valuation.
Flood Risk, the Ettrick Water and Mortgage Applications
Water shapes this part of the Borders.
Philiphaugh lies near the Ettrick Water, and flood-management work in the Selkirk area has included measures intended to reduce flooding affecting Philiphaugh, Bannerfield and Riverside.
That does not mean every Philiphaugh property is at significant flood risk.
Nor should the existence of flood defences be treated as proof that a particular home will be acceptable to every lender or insurer.
The correct question concerns the individual property.
Where relevant, buyers may want to establish:
- the property’s specific flood history;
- current flood mapping;
- whether buildings insurance is readily available;
- any comments in the Home Report;
- whether a lender’s valuer raises the issue; and
- whether additional evidence is required.
Insurance matters because lenders normally require suitable buildings cover for mortgaged residential property.
A property can therefore satisfy affordability calculations yet still require more investigation before mortgage terms are confirmed.
Philiphaugh’s Battlefield and Historic Landscape
Philiphaugh is also historically distinctive.
The Battle of Philiphaugh took place in 1645, and the battlefield is included in Scotland’s Inventory of Historic Battlefields. Historic Environment Scotland identifies the low-lying land south-west of Selkirk as the battle’s established general location.
Historical designation does not prevent ordinary mortgage lending.
However, archaeology, planning restrictions or development limitations can become relevant when someone intends to alter, extend or substantially redevelop a property.
Previous planning assessments around Philiphaugh have specifically considered the historic battlefield, archaeology, ecology and the nearby River Tweed Special Area of Conservation.
For a normal residential purchase, these matters may have little practical effect.
For a buyer planning substantial redevelopment, they can become much more important.
The mortgage should therefore be considered alongside what you intend to do after receiving the keys.
What a Mortgage Broker in Philiphaugh Needs to Know Before Applying
The strongest mortgage application usually has the fewest unanswered questions.
Before recommending a lender, an adviser may need to understand:
Your income
This can include:
- basic salary;
- overtime;
- commission;
- bonuses;
- pension income;
- benefits accepted by the lender;
- self-employed profits;
- company director income;
- contractor earnings; and
- income from other property.
Different lenders calculate usable income differently.
This is particularly important for self-employed borrowers, contractors and applicants with several sources of income.
Your deposit
The amount matters, but so does its origin.
Your deposit might come from:
- personal savings;
- a previous property sale;
- investments;
- inheritance;
- a gifted deposit;
- existing property equity; or
- another acceptable source.
The lender, solicitor and adviser may require evidence of where the funds came from.
Your commitments
Existing borrowing can affect affordability even where monthly income appears strong.
That can include:
- personal loans;
- credit cards;
- car finance;
- student finance;
- maintenance commitments;
- existing mortgages; and
- other regular financial obligations.
The property
The lender may also need accurate information about:
- purchase price;
- property type;
- construction;
- age;
- land;
- outbuildings;
- occupancy;
- access;
- private services;
- proposed letting;
- business activity; and
- unusual title conditions.
Mortgage advice works best when personal affordability and property suitability are examined together.
First-Time Buyers in Philiphaugh
Buying a first home can make mortgage terminology feel more important than it really is.
Loan-to-value, affordability models, stress testing and product fees all matter.
But the underlying decision is simpler:
Can you buy the home without making the mortgage itself the dominant feature of your finances?
Across the Scottish Borders, first-time buyers paid an average of around £150,000 in August 2026, compared with approximately £195,000 across all buyers. These are regional averages, not valuations for Philiphaugh itself.
Before making an offer, a first-time buyer may benefit from understanding:
- realistic borrowing capacity;
- likely deposit requirement;
- monthly payments;
- purchase costs;
- mortgage fees;
- valuation requirements;
- the Scottish Home Report;
- the difference between an Agreement in Principle and a mortgage offer; and
- what happens if the lender values the property below the agreed purchase price.
You can also explore specialist first-time buyer mortgage advice before deciding which lenders to approach.
Checking Mortgage Rates Before Choosing a Deal
A low advertised rate is not necessarily the lowest-cost mortgage.
Fees, incentives, loan size, mortgage term, and the period you compare can change the answer.
Someone borrowing £80,000 may reach a different conclusion than someone borrowing £300,000, even when both consider the same two products.
Before deciding, compare:
- initial interest rate;
- monthly payment;
- arrangement fee;
- valuation fee where applicable;
- incentives;
- early repayment charges;
- product period;
- total cost during that period; and
- what happens when the initial deal ends.
For a broader view of products currently available, see UK mortgage rates and deals.
Rates can change quickly and an advertised product does not mean you will qualify for it. Eligibility depends on the lender’s criteria, affordability assessment and the property.
Remortgaging a Home in Philiphaugh
A mortgage approaching the end of its initial deal creates a decision point.
Doing nothing is still a decision.
You may want to compare:
- a new deal from your existing lender;
- remortgaging to another lender;
- changing the mortgage term;
- repaying part of the balance;
- borrowing additional funds;
- moving from interest-only to repayment where suitable; or
- restructuring other borrowing.
If your current deal is nearing its end, mortgage rate-ending advice can help you explore your options.
The right comparison should include fees and early repayment charges, not simply the new headline rate.
Buying a Property You Intend to Let
A property bought for letting requires a different mortgage assessment from a home you plan to occupy yourself.
The lender may consider expected rent, property type, landlord experience, tax structure and the proposed tenancy.
The right specialist route depends on what you’re buying.
Relevant adviser searches include:
- first-time landlord mortgage advice if this will be your first rental property;
- portfolio landlord mortgage advice where you already hold several mortgaged properties;
- HMO mortgage advice where the intended occupation requires specialist HMO lending;
- limited company buy-to-let advice when purchasing through a company; and
- non-UK resident buy-to-let advice where residency creates additional lender requirements.
The mortgage should match the intended use from the outset.
When Philiphaugh Property Plans Become More Complex
Not every property transaction belongs inside a standard residential or buy-to-let mortgage.
Someone purchasing land, converting buildings, acquiring commercial premises or completing major development may require a different type of finance.
Depending on the project, useful specialist searches include:
- short-term buy-to-let bridging finance;
- commercial bridging finance;
- development finance advice;
- owner-occupied commercial mortgage advice;
- commercial investment property finance; and
- business loan advice.
These are different forms of borrowing with different risks and lending criteria.
A specialist adviser can help determine which type of finance best matches the transaction before applications begin.
Protecting the Mortgage and the People Behind It
Getting a mortgage creates an asset.
It can also create a long-term financial commitment.
That is why protection shouldn’t be an afterthought added once the mortgage is complete.
Depending on individual circumstances, discussions may include:
- life insurance;
- critical illness cover;
- income protection; and
- other cover designed around the household’s financial commitments.
The purpose is not to insure a mortgage rate.
It is to consider what would happen to the people relying on the household income if life changed unexpectedly.
You can speak with protection mortgage brokers to explore cover that may suit your circumstances.
Insurance policies have different definitions, exclusions, qualifying periods and conditions. Advice should reflect the individuals being protected, not simply match the mortgage balance.
Is the Closest Adviser Automatically the Best Adviser?
Geography can help.
Experience can matter more.
A local adviser may understand Selkirk and the surrounding Borders market, but specialist knowledge becomes particularly valuable where the borrower or property is less conventional.
When choosing a Mortgage Broker in Philiphaugh, consider:
- whether they regularly advise on your type of mortgage;
- whether they understand the property’s characteristics;
- the range of lenders they can consider;
- how their fees work;
- how they communicate;
- whether telephone or online appointments are available;
- what information they need before recommending a lender; and
- whether they hold the appropriate permissions for the advice required.
A good adviser should be willing to explain not only which mortgage they recommend, but why it suits the circumstances.
Distance is measurable.
Relevance is more valuable.
Moving to the Wider Selkirkshire Area
Philiphaugh’s appeal is closely tied to Selkirk itself and the countryside beyond.
The area sits between the amenities of an established Borders town and the Ettrick and Yarrow valleys, with farmland, woodland and hills beginning almost immediately west of the settlement. Philiphaugh Estate is about two miles west of Selkirk, near where the Yarrow and Ettrick meet.
If you’re considering the area rather than a particular property, our guide to moving to Selkirkshire provides more context on housing, transport, local services, and lifestyle.
Location can tell you where you might want to live.
Mortgage advice helps establish what you can sensibly do once you find the right home.
Three Questions Worth Asking Before Choosing a Mortgage
Does the lender suit the property as well as the borrower?
A high income and deposit don’t guarantee every lender will accept every property. Construction, condition, acreage, use and valuation can all affect the decision.
Am I comparing the complete mortgage cost?
Consider the rate alongside product fees, incentives, early repayment charges, and how long you expect to keep the deal.
Would the mortgage still feel manageable if circumstances changed?
Affordability calculations establish what a lender may allow.
Your own financial planning should also consider what level of borrowing you are comfortable maintaining.
The largest available mortgage and the right mortgage are not necessarily the same amount.
Speak to a Mortgage Broker in Philiphaugh
A mortgage is usually agreed in numbers, but lived with in years.
That is why the strongest starting point is not simply asking which lender has the lowest rate today.
It’s about understanding what you are buying, what you can comfortably afford, how the lender will assess the property, and whether the mortgage leaves enough room for everything that comes afterwards.
A Mortgage Broker in Philiphaugh can assess your circumstances, property, and plans before identifying lenders whose criteria may suit you.
Whether you are buying your first home, moving within TD7, remortgaging, purchasing a rental property or financing something more specialist, the objective should remain the same:
find borrowing that fits the property without losing sight of the person who has to repay it.