
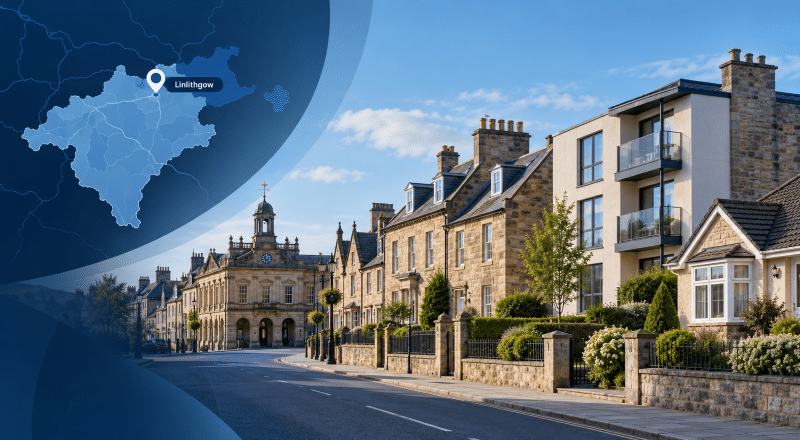
A Mortgage Broker in Linlithgow can help turn a property decision into a well-considered financial decision. A home is tied to a location, but the mortgage behind it must accommodate income, affordability, lender criteria, and plans that may change over many years.
Linlithgow has a housing market that differs noticeably from parts of wider West Lothian. Historic properties around the town centre sit alongside conventional family homes, flats and newer housing. That variety can make property type, condition, valuation and location relevant to lender assessment.
Connect Experts helps you find mortgage advisers who cover Linlithgow and compare them by mortgage expertise, location, and other practical preferences. Connect Experts is a directory and matching platform; the mortgage advice itself is provided by the adviser or firm you choose.
At a glance: Mortgage Broker in Linlithgow
- Linlithgow’s principal postcode district is EH49.
- The town contains historic stone buildings, flats, traditional family housing and more modern developments.
- Linlithgow has two designated conservation areas: Palace & High Street and Upper Linlithgow & Union Canal.
- The average West Lothian house price was approximately £227,000 in July 2026, according to provisional UK House Price Index data.
- Linlithgow values can sit materially above the wider West Lothian average; ESPC reported an average of £318,925 for properties marketed and sold through ESPC in the three months to 31 July 2026.
- Recent transactions also show substantial variation between flats, conventional homes and higher-value detached property.
- Rail access towards Edinburgh and Glasgow can make the town relevant to households whose employment is based outside West Lothian.
- Adviser experience with the property or borrower may be more important than simply choosing the nearest adviser.
Understanding the Linlithgow Mortgage Market
Linlithgow is not a uniform mortgage market.
West Lothian’s provisional average house price stood at around £227,000 in July 2026, up 2.3% from £222,000 a year earlier. Across Scotland, the corresponding average was approximately £196,000.
Linlithgow-specific figures indicate a higher-value local market. ESPC calculated an average selling price of £318,925 for the three months ending July 2026, while Rightmove reported an overall sold-price average of £315,476 over its preceding 12-month period. These datasets use different methodologies and time periods, so they should not be treated as identical measures, but both illustrate why local values can differ significantly from the West Lothian-wide average.
For a borrower, the important figure is ultimately the lender’s valuation of the particular property being purchased or remortgaged.
Historic property and conservation areas
Linlithgow’s built environment is especially relevant to mortgage research.
West Lothian Council identifies both the Linlithgow Palace & High Street Conservation Area and the Upper Linlithgow & Union Canal Conservation Area. The council also confirms that Article 4 Directions apply in these areas, introducing additional planning controls over certain alterations.
Conservation-area status does not prevent mortgaging a property. However, a historic building could raise additional questions about:
- construction materials;
- roof and structural condition;
- previous alterations;
- listed-building status where applicable;
- maintenance obligations;
- valuation;
- insurance; and
- whether proposed works require consent.
A mortgage adviser does not replace a surveyor, solicitor, or planning professional, but can help identify lenders whose criteria match the property you’re considering.
You can review West Lothian Council’s information on Linlithgow and West Lothian conservation areas.
Mortgage Factors Worth Considering in Linlithgow
A lender assesses the borrower and property together.
That means a high income does not automatically compensate for a property outside a lender’s criteria, just as a conventional property does not remove the need to demonstrate affordability.
Deposit and loan-to-value
Your deposit determines the initial loan-to-value, or LTV.
A larger deposit can reduce LTV, but lenders can still base decisions on income, existing commitments, credit history, age, mortgage term, and the property’s acceptability as security.
Commuter income
Linlithgow’s rail connections can suit people working beyond the immediate town, including those travelling towards Edinburgh or Glasgow. National Rail provides journey planning directly from Linlithgow to Glasgow, demonstrating the town’s connection to the central Scotland rail network.
Location generally matters less to mortgage affordability than the sustainability and evidence of the income itself. Employment involving bonuses, overtime, allowances, commission or more than one income source may therefore require closer assessment of individual lender criteria.
Self-employed and company-director income
Self-employed applicants can encounter considerable differences between lenders.
Underwriting might consider:
- trading history;
- salary and dividends;
- net profit;
- share of company profit;
- retained profits;
- recent accounting performance; and
- changes to the business.
A specialist adviser can establish which parts of the applicant’s financial position a particular lender is prepared to use before an application is submitted.
Finding a Mortgage Broker in Linlithgow
Choosing a Mortgage Broker in Linlithgow should not simply mean selecting whichever adviser has an office closest to EH49.
Relevant experience can be more useful.
Someone buying a conventional family home may have relatively straightforward requirements. A client buying an older conservation-area property, using company-director income, arranging a larger loan or purchasing an investment property may need a different adviser skill set.
The Connect Experts directory allows you to search for a mortgage adviser by location and expertise.
You can also use the dedicated mortgage adviser location search to compare advisers who cover your area.
First-Time Buyers in Linlithgow
For a first-time buyer, the purchase price is only one part of affordability.
Mortgage planning should also account for:
- deposit size;
- monthly mortgage payments;
- legal costs;
- valuation or survey costs;
- moving expenses;
- ongoing maintenance; and
- an allowance for unexpected expenditure.
Scotland also has its own property-purchase process, including Home Reports and the offers-over system commonly encountered in the market. Buyers should obtain appropriate legal advice on the Scottish conveyancing process.
A mortgage adviser can assess the mortgage side of the transaction and explain how lender affordability and loan-to-value requirements apply to your circumstances.
Moving Home in EH49
Existing homeowners can face a different problem: the purchase and mortgage decisions have to work together.
Before committing to the next property, it may be sensible to establish:
- the outstanding balance on the existing mortgage;
- whether early repayment charges apply;
- whether the current mortgage is portable;
- how much equity is expected after the sale;
- whether additional borrowing is required; and
- whether keeping the existing mortgage remains competitive.
Portability does not automatically guarantee approval. A lender will normally reassess affordability and the new property when an existing customer moves home.
Remortgaging a Linlithgow Property
A remortgage can be prompted by an approaching fixed-rate expiry, additional borrowing requirement or a change in household finances.
The starting point is usually the existing mortgage.
Check:
- the current balance;
- remaining term;
- rate-ending date;
- early repayment charges;
- anticipated property value; and
- additional borrowing requirements.
This gives an adviser a clearer basis for comparing the existing lender’s options with potentially suitable alternatives.
Higher-Value Homes and Complex Borrowing
Linlithgow also has a higher-value segment that is not evident from West Lothian’s overall average.
Rightmove’s recent sold-price data, for example, includes detached transactions substantially above the town average, including individual EH49 sales exceeding £500,000 and £900,000. Individual transactions should not be treated as representative of every property, but they demonstrate the breadth of the local market.
Higher property value alone does not make somebody a high-net-worth mortgage customer under regulatory definitions. However, clients requiring larger loans may also have more complex income or asset arrangements.
Company directors, senior executives, entrepreneurs, investors and clients with bonuses, dividends or investment income may therefore benefit from searching for advisers experienced with high-net-worth and complex mortgage cases.
The objective is not automatically to use a private bank or specialist lender. It is to identify underwriting that appropriately reflects the client’s actual financial circumstances.
Mortgage Protection Advice
Getting the mortgage agreed addresses one financial question. Protecting the household’s ability to manage that commitment addresses another.
Life events do not necessarily arrive at convenient points in a mortgage term.
Depending on personal circumstances, protection planning can include:
- life insurance;
- critical illness cover;
- income protection;
- family income benefit; and
- mortgage payment protection.
A protection adviser can consider the mortgage balance, term, household income, dependants, employment and existing cover before making a recommendation.
Connect Experts allows borrowers to find advisers offering mortgage and protection advice.
Protection eligibility, exclusions, premiums and benefits vary between insurers, so the suitability of cover should be assessed individually.
Later-Life Borrowing and Equity Release in West Lothian
For some older homeowners, the mortgage question changes over time.
Instead of borrowing primarily to purchase a home, the discussion might involve repaying an existing mortgage, releasing capital, helping family members, making adaptations or supplementing retirement finances.
Equity release is a specialist area and isn’t suitable for everyone. It can reduce the value of an estate and may affect entitlement to means-tested benefits, so personalised advice is important before deciding.
Homeowners in Linlithgow can read more about Equity Release Advisers in West Lothian through Connect Lifetime.
This is a separate specialist advice journey, not an alternative that should automatically replace a conventional residential mortgage.
Why Adviser Expertise Can Matter More Than Distance
A property postcode tells an adviser where the security is located. It does not explain the borrower.
Two buyers considering similar Linlithgow homes could have completely different lending requirements because one receives PAYE income while the other runs a limited company, one has a 25% deposit while another has 10%, or one is buying a standard property while the other is purchasing an older converted building.
That is why finding the right Mortgage Broker in Linlithgow is ultimately about matching the case to relevant experience.
Telephone and video advice also mean an adviser doesn’t necessarily need to be based in EH49. Connect Experts confirms that users can search by location while also comparing mortgage expertise, language and other preferences.
Find a Mortgage Broker in Linlithgow
A good mortgage decision begins by understanding both sides of the application: the person borrowing and the property being financed.
Use Connect Experts to compare advisers whose experience matches your circumstances, whether you are buying your first home, moving within West Lothian, remortgaging, self-employed or arranging more complex borrowing.
Find a mortgage adviser through Connect Experts.




