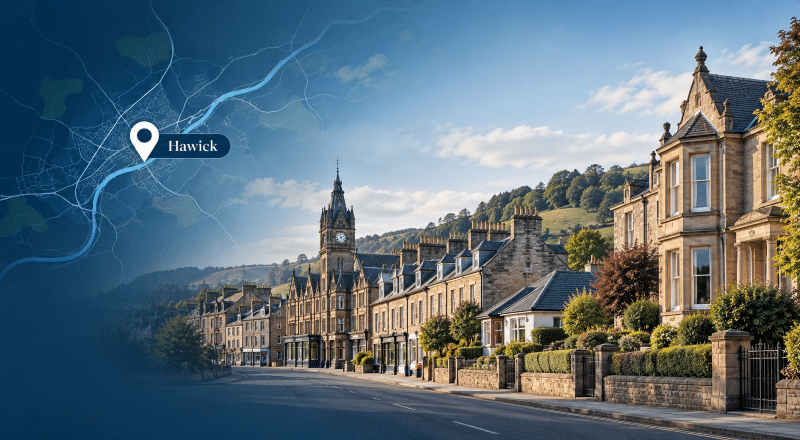
A Mortgage Broker in Hawick can turn a property search into a lending plan by looking beyond the asking price to the home, the borrower, and how they fit together.
A mortgage is rarely just a calculation. It is a long commitment secured against a very specific building. In Hawick, that distinction matters. A conventional house in Burnfoot, a Victorian property near the historic centre, a flat above commercial premises or a home close to the Teviot can present very different questions for a lender.
The useful starting point is therefore not simply “what is the lowest rate?” but “what will a lender need to understand before it is willing to lend?”
At a glance: Mortgage Broker in Hawick
- TD9 is Hawick’s principal postcode district.
- Hawick is the main settlement in the Teviot and Liddesdale area of the Scottish Borders.
- The town centre conservation area includes the High Street and historic core, with Victorian properties, sandstone construction and surviving buildings associated with Hawick’s textile history.
- The amended Hawick Conservation Area includes 93 listed properties, including three Category A buildings.
- The average Scottish Borders house price was about £195,000 in August 2026, while first-time buyers paid about £150,000 on average.
- Hawick’s own recorded sold-price average over the last year was approximately £137,519, showing why a town-level property shouldn’t be judged solely against the wider Borders average.
- A Scottish Home Report normally provides a Single Survey, Energy Report and Property Questionnaire before an offer is made.
- Hawick’s relationship with the River Teviot and Slitrig Water makes property-specific flood and insurance checks worth understanding, despite the substantial flood-protection work completed in the town.
- Adviser experience can matter more than simply choosing the person geographically closest to you.
Hawick homes reward detail, not assumption
Hawick’s housing reflects its development as a Border market and textile town.
Scottish Borders Council describes a conservation area covering the High Street and historic core. Its building stock includes Victorian properties, sandstone and whinstone construction, traditional terraces, shops and surviving textile-related buildings. Scottish Borders Council’s Hawick Conservation Area information
That variety can matter to a mortgage lender.
A straightforward modern house may fit many mainstream lending policies. An older stone property, listed building, converted commercial building, flat above retail premises or home with unusual access may require more careful lender selection.
Before an application, useful details can include:
- construction type and roof covering;
- Home Report valuation and condition ratings;
- whether the property is listed or within the conservation area;
- evidence of alterations and relevant permissions;
- location above, beside or close to commercial premises;
- previous flooding and current building-insurance terms;
- title conditions, access and shared maintenance responsibilities;
- any business use, annexe, letting arrangement or land attached to the property.
The point is not that an older or unusual home cannot be mortgaged. The lender must be comfortable with both the property as security and its future saleability.
Where a Mortgage Broker in Hawick can add value
Different lenders can interpret the same borrower and property differently.
One lender may accept a particular construction type or proximity to commercial premises while another may not. Some may be comfortable with smaller flats, older stone homes, inherited deposits or irregular income. Others can apply narrower criteria.
A broker can help compare:
- whether the property is acceptable to the lender;
- how affordable borrowing is calculated;
- the deposit required;
- the interest rate and product fee;
- valuation requirements;
- early repayment charges;
- incentives such as cashback or valuation contributions;
- the overall cost during the period you expect to keep the mortgage.
For a current starting point, compare live UK mortgage rates and costs.
A headline interest rate should not be considered in isolation. Fees, loan-to-value, lender criteria and how long you expect to keep the product can change which mortgage represents better value. The rate results are illustrative and do not confirm eligibility.
Buying in Scotland: the Home Report comes first
The Scottish buying process gives purchasers useful property information before an offer is made.
A Home Report normally contains:
- a Single Survey;
- an Energy Report;
- a Property Questionnaire.
The Single Survey gives information about condition and valuation. However, a Home Report valuation does not remove the mortgage lender’s own requirements.
Depending on the property, lender, and report age, further evidence or valuation work may still be required.
Read the Scottish Government’s Home Report guidance before making assumptions about what the report does and does not provide.
Your solicitor also plays a central role in the Scottish buying process, including submitting an offer and progressing the legal work through missives.
Remember LBTT, not SDLT
Property purchases in Scotland can attract Land and Buildings Transaction Tax (LBTT) rather than Stamp Duty Land Tax.
The Additional Dwelling Supplement may also apply where the transaction involves an additional residential property, subject to the rules applying at the effective date.
Revenue Scotland provides a property transaction and LBTT calculator, along with current LBTT guidance.
That distinction is particularly important for landlords and buyers moving to Scotland from elsewhere in the UK.
What the latest Hawick and Borders property figures tell us
Market statistics provide context. They don’t value the specific house you want to buy.
The Office for National Statistics reported an average house price of about £195,000 across the Scottish Borders in August 2026, up 3.6% over the year.
Average prices varied considerably by property type:
- Detached: £374,000
- Semi-detached: £231,000
- Terraced: £189,000
- Flats and maisonettes: £112,000
First-time buyers paid approximately £150,000 on average, while homes bought with mortgages averaged about £202,000.
Hawick itself presents a different picture.
Rightmove’s recorded sold-price data showed an overall Hawick average of approximately £137,519 over the previous year. Flats averaged around £78,493, terraced properties £148,580 and detached homes £280,917.
Different sources use different periods, methodologies and geographical boundaries, so these figures should not be treated as interchangeable.
They do demonstrate something useful: the individual property matters more than the regional headline number.
First-time buying in Hawick: understand the gap between price and value
For a first-time buyer, the deposit is only one part of the cash requirement.
Your budget may also need to accommodate:
- solicitor’s fees;
- mortgage fees;
- moving costs;
- valuation costs where applicable;
- LBTT where due;
- repairs identified by the Home Report;
- money required if you offer above the valuation.
That last point deserves particular attention.
A lender will normally calculate the mortgage against the value it accepts for lending purposes. Paying more for a property does not automatically mean the lender will fund the same percentage of the higher offer.
For example, an attractive Hawick property marketed competitively could generate an offer above its Home Report valuation. The buyer may need to cover the difference from their own resources.
Before submitting an offer, understand:
- your maximum affordable mortgage;
- the deposit remaining after fees;
- whether the lender accepts the property;
- how much additional cash an above-valuation offer would require;
- whether your loan-to-value changes;
- whether that change affects the mortgage products available.
Confidence before commitment comes from knowing those numbers.
Moving to a larger or more individual TD9 home
Home movers face a different calculation.
The equity shown in your present home is not necessarily the amount available for your next deposit.
You may need to deduct:
- your existing mortgage;
- estate-agency costs;
- legal fees;
- early repayment charges;
- moving expenses;
- other borrowing being repaid from the sale.
The next property may also change the mortgage options.
Moving from a conventional house to a detached property with land, an older rural-edge home, a building with outbuildings or a property combining residential and commercial characteristics can narrow the suitable lender pool.
A mortgage adviser can help you test the new property and borrowing requirements together, rather than relying on assumed mortgage availability.
When your current mortgage rate is ending
The end of a mortgage product is a decision point. It doesn’t automatically mean switching lenders is the right decision.
Compare any product-transfer options offered by the existing lender against remortgage opportunities elsewhere.
Consider:
- the new interest rate;
- product fees;
- valuation costs;
- legal costs;
- early repayment charges;
- loan-to-value;
- additional borrowing requirements;
- how long you expect to keep the new deal.
If your current product is approaching expiry, use the mortgage rate ending adviser search to find advisers experienced in reviewing the next step.
This can be particularly useful where circumstances have changed since the original mortgage.
Self-employment, lower or higher income, new credit commitments, additional borrowing, or a change in property use can all change your options.
Letting property in and around Hawick
A property that works perfectly well as somebody’s home does not automatically fit buy-to-let criteria.
Landlords need to consider expected rent, tenancy arrangements, property condition, lender stress testing, deposit, ownership structure and tax position.
The property must also satisfy the lender’s security requirements.
Depending on your circumstances, specialist searches include:
- portfolio landlord mortgage advisers for borrowers already holding several rental properties;
- limited company buy-to-let advisers where a property is being purchased through a company;
- HMO mortgage advisers where the intended occupation requires specialist HMO lending.
These are different lending propositions.
A lender suitable for a single property let to one household may not be suitable for a larger portfolio, company-owned property or HMO.
Some buy-to-let lending is not regulated by the Financial Conduct Authority.
Hawick’s commercial heritage can create specialist borrowing needs
Hawick’s textile and trading history remains visible in its buildings.
The town centre includes former industrial premises and properties where commercial and residential uses sit close together. Scottish Borders Council’s conservation-area record specifically identifies surviving textile buildings, including structures associated with the town’s former mills.
If a transaction isn’t a conventional residential purchase, specialist finance may be appropriate.
For example:
- Use the owner-occupied commercial mortgage adviser search when a business is acquiring premises to occupy.
- Use the development finance adviser search where a qualifying conversion, refurbishment or development project requires specialist funding.
The intended use of the property should be clear from the beginning.
Trying to fit a commercial, mixed-use, or development proposition into an unsuitable residential mortgage can create unnecessary difficulties later.
Commercial mortgages and certain business lending arrangements may not be regulated by the FCA.
Flood history should be checked property by property
The River Teviot and Slitrig Water define Hawick, but they also mean flood information deserves attention when considering individual homes.
A substantial Hawick Flood Protection Scheme has been delivered, alongside wider infrastructure and active-travel improvements. Scottish Borders Council has described the scheme as protecting hundreds of homes and businesses and improving the town’s resilience.
That does not mean every TD9 property has the same risk profile.
For a particular purchase, buyers may still need to consider:
- the property’s precise location;
- historical flooding;
- available flood-risk information;
- building-insurance availability and excesses;
- lender requirements;
- information contained within the Home Report or legal searches.
Protection infrastructure can change risk. It does not remove the need to understand the individual property.
Protection should be part of the mortgage conversation
A mortgage creates a financial commitment that may continue for decades.
Protection advice asks a different question: what happens to that commitment if life changes unexpectedly?
An adviser can discuss relevant options such as life cover, critical illness cover, and income-related protection, taking into account the mortgage, earnings, dependants, existing policies, and household budget.
Use the protection mortgage brokers search to find advisers who can discuss mortgage-related protection.
Protection products have eligibility requirements, exclusions and policy terms. Appropriate cover depends on personal circumstances, not simply on matching the mortgage balance.
Later-life borrowing and equity release
Later-life borrowing deserves its own assessment rather than being treated as an extension of a standard residential mortgage.
Connect Lifetime has a detailed guide to equity release advisers in Selkirkshire covering issues such as property eligibility, loan-to-value, rolled-up interest, drawdown, inheritance and potential effects on means-tested benefits.
For a Hawick TD9 property, confirm that the adviser covers your address and that the particular property meets the provider’s criteria.
This matters because older stone properties, unusual construction, land, outbuildings, access arrangements, commercial use, and flood considerations can all affect later-life lender criteria.
Equity release can reduce the value of your estate and may affect your entitlement to means-tested benefits.
A lifetime mortgage is a loan secured against your home. Regulated equity-release advice should consider alternatives and the amount potentially available.
Choosing an adviser for the property you actually want to finance
The nearest adviser is not automatically the best match.
When comparing advisers, ask whether they regularly handle the type of mortgage and property involved. A Mortgage Broker in Hawick should be able to explain not only rates but also how the property’s construction, valuation, location and intended use could influence lender choice.
Consider:
- experience with your type of mortgage;
- familiarity with the Scottish buying and remortgage process;
- experience with older, listed, rural-edge or mixed-use property where relevant;
- access to lenders appropriate to the case;
- fees and when they become payable;
- telephone, online or face-to-face communication;
- whether protection advice is available;
- the adviser’s or firm’s regulatory permissions.
Connect Experts is a mortgage adviser directory and matching platform. It does not provide mortgage advice directly. Advice is provided by the adviser or firm you choose.
Search for a Mortgage Broker in Hawick
The strongest mortgage application often answers key questions before they become obstacles.
If you are buying, moving, remortgaging, investing or considering a more specialist property in TD9, use Connect Experts to compare advisers by location and expertise.
Begin with the property, the purpose and the numbers.
Then compare the mortgages that genuinely fit.