A Mortgage Broker in Galashiels can turn a simple truth into a practical plan: the right home isn’t just one you can buy; it’s one you can afford to keep.
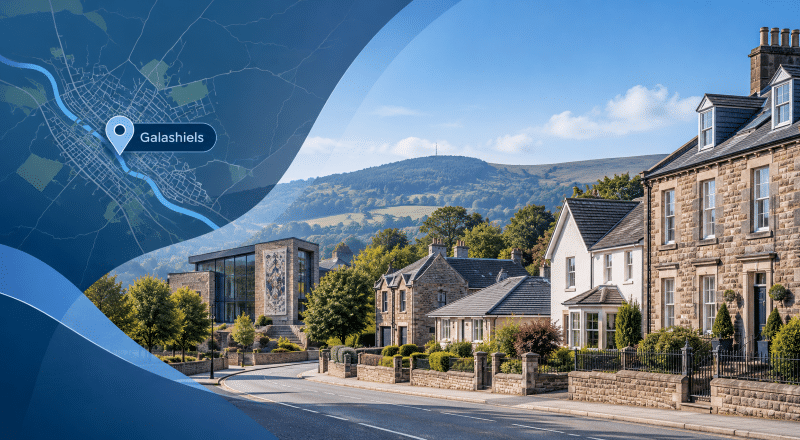
Galashiels gives buyers a different proposition from many smaller communities across Selkirkshire. It combines established residential streets, traditional stone buildings, newer housing, shops and services, and direct rail connections to Edinburgh.
That variety creates choice. It also means the property, the mortgage and the way you intend to use the home should be considered together.
Whether you are buying for the first time, moving, remortgaging, or purchasing an investment property, good advice starts with understanding what you’re trying to achieve.
At a glance: Mortgage Broker in Galashiels
- Galashiels is one of the principal towns serving the Scottish Borders.
- The town sits within the TD1 postcode area, providing a clear local search signal.
- The Borders Railway gives Galashiels a direct rail connection towards Edinburgh.
- Housing includes flats, terraces, traditional stone homes, semi-detached houses and newer residential development.
- A substantial part of historic central Galashiels lies within a designated conservation area.
- The average property price in the Scottish Borders was approximately £195,000 in August 2026.
- First-time buyers across the Scottish Borders paid an average of approximately £150,000 during the same month.
- Mortgage buyers paid an average of approximately £202,000.
- Home Reports, property condition, and valuation can influence how much a lender is willing to lend.
- The cheapest mortgage rate isn’t automatically the lowest overall cost.
Galashiels Property Can Tell More Than One Story
Two homes with similar asking prices can produce very different mortgage questions.
Central Galashiels includes traditional properties constructed from stone, slate and other materials associated with the town’s historic development. Scottish Borders Council identifies a substantial conservation area around streets including High Street, Channel Street, Bank Street, Bridge Street and Overhaugh Street.
Elsewhere, buyers may find more conventional semi-detached and detached housing, ex-local-authority property, modern development, and homes on the town’s edges.
A Mortgage Broker in Galashiels can therefore help you consider not only how much you want to borrow, but whether the property itself presents anything a lender may examine more closely.
That could include:
- construction type;
- property condition;
- significant repairs;
- roof condition;
- previous alterations;
- flats above or beside commercial premises;
- title restrictions;
- access arrangements;
- flood considerations;
- letting or business use; and
- whether the valuation supports the agreed purchase price.
An older home is not automatically difficult to mortgage. However, understanding the property before approaching a lender can prevent avoidable complications later.
Read the Home Report Before You Read Too Much Into the Asking Price
Buying in Scotland gives purchasers an important source of information before an offer is made.
The seller’s Home Report normally contains a single survey and valuation, a property questionnaire and an energy report.
Read it carefully.
The valuation matters because lenders usually base their loan-to-value calculation on an acceptable valuation rather than simply the amount you agree to pay.
For example, if competition pushes an offer above the Home Report valuation, you may need to fund more of the purchase from your own resources.
Repairs also deserve attention. A surveyor may identify issues that require immediate or future work. Those costs can affect how much cash you want to keep after completion.
Your solicitor deals with the Scottish conveyancing process, including formal offers and missives. Your mortgage adviser deals with the financing. The two parts of the transaction need to work together.
First-Time Buyers in Galashiels: Prepare Before the Closing Date
A first purchase is often described as a step onto the property ladder. In reality, it is a series of smaller decisions that should all point in the same direction.
Before viewing seriously, understand:
- your available deposit;
- the approximate mortgage amount you may be able to support;
- your monthly budget;
- purchase costs;
- the effect of existing credit commitments;
- what evidence a lender may request; and
- how much money you want to retain after completion.
The latest published figures put the average price paid by first-time buyers across the Scottish Borders at approximately £150,000 in August 2026. Regional averages provide useful context, but they don’t value a particular Galashiels home.
If this is your first purchase, an adviser specialising in first-time buyer mortgage advice can help you understand your borrowing position before you become emotionally committed to a property.
That preparation matters when a seller sets a closing date and purchasers need to decide quickly.
Compare the Mortgage, Not Just the Headline Rate
Rates attract attention because they are easy to compare. Costs require more thought.
A lower headline rate can come with a larger arrangement fee. Another mortgage may have a slightly higher rate but lower upfront costs or incentives.
The meaningful comparison depends on your circumstances and how long you expect to keep the deal.
Consider:
- the initial interest rate;
- monthly repayment;
- lender arrangement fees;
- valuation fees where applicable;
- cashback or incentives;
- early repayment charges;
- the period before the rate changes; and
- the total cost over the period you expect to hold the mortgage.
You can compare current UK mortgage rates and estimated costs before speaking with an adviser.
The results should be treated as a starting point rather than confirmation that you qualify. Lenders still assess your income, expenditure, credit profile, deposit and the property itself.
When Your Current Mortgage Deal Is Coming to an End
A remortgage decision is not simply about finding a different lender.
Start early enough to compare your existing lender’s options with alternatives available elsewhere.
If your current deal is nearing expiry, a mortgage rate-ending adviser can help you understand what happens next.
You may want to consider:
- the outstanding mortgage balance;
- your current property value;
- remaining mortgage term;
- early repayment charges;
- product fees;
- whether your income has changed;
- plans for home improvements; and
- whether you expect to move again soon.
Homeowners who need a broader review can also explore remortgage mortgage advice.
The lowest rate today isn’t necessarily the best deal for the years ahead.
Buying a Property You Intend to Let
Galashiels serves a substantial local population and has road, bus and rail links to other parts of the Borders and towards Edinburgh. However, you should still assess an investment property on its own merits rather than on assumptions about an area.
Lenders can consider expected rent, property type, applicant experience and the proposed ownership structure.
Depending on your circumstances, relevant specialist advice can include:
- portfolio landlord mortgage advice where you already own several rental properties;
- first-time landlord advice when buying your first rental property;
- HMO mortgage advice where the property will operate as a house in multiple occupation;
- limited company buy-to-let advice where a company may purchase the property; and
- non-UK resident buy-to-let advice where the borrower lives overseas.
Tax treatment and ownership structure can have consequences beyond the mortgage, so obtain appropriate tax and legal advice where required.
When the Property Is Part of a Wider Business Plan
Not every property transaction fits neatly into a standard residential or buy-to-let mortgage.
You may be purchasing premises for your own business, acquiring a commercial investment, refinancing an existing property or funding improvement works before longer-term finance becomes suitable.
Depending on the transaction, specialist routes can include:
- business loan advice;
- short-term commercial bridging finance;
- development finance advice;
- owner-occupied commercial mortgage advice; and
- commercial investment property finance.
Where a property is being bought specifically to let and short-term funding is required, buy-to-let bridging loan advice may also be relevant.
The appropriate finance depends on the property, its condition, your exit strategy and what you intend to do with it.
Property Location Deserves Its Own Checks
Galashiels grew around the Gala Water, and Scottish Borders Council confirms that a flood prevention scheme for the town was completed in 2014.
That does not mean every home in Galashiels has a flood issue.
It does mean buyers should investigate the individual address rather than making assumptions from the town name alone. Your solicitor, surveyor and insurer may all provide information relevant to the property.
Likewise, a conservation-area address does not automatically prevent mortgage lending. It can, however, make the history of alterations, building condition and permitted work more important.
Good lending decisions start with the property itself, not the postcode alone.
Protect the Home as Well as the Mortgage
Getting the keys solves one problem. Keeping the household financially resilient is another.
Mortgage planning should include a conversation about what would happen if illness, injury, loss of income or death affected the household’s ability to meet its commitments.
A specialist protection mortgage broker can discuss options such as:
- life insurance;
- critical illness cover;
- income protection; and
- mortgage-related protection.
The appropriate cover depends on your mortgage, income, dependants, employment, existing policies, budget and personal circumstances.
Protection should be considered for what it is intended to do rather than simply because a mortgage has been arranged.
Later-Life Borrowing and Equity Release in Selkirkshire
A mortgage conversation can change as life changes.
Older homeowners may consider retirement borrowing, repaying an existing mortgage, helping family members financially, adapting their home, or releasing some of the wealth tied up in their property.
Where appropriate, homeowners can explore equity release advisers in Selkirkshire through Connect Lifetime.
Equity release is not suitable for everyone. A lifetime mortgage can affect your estate’s value, future options, and entitlement to means-tested benefits. Alternatives should therefore be considered before a recommendation is made.
Specialist regulated advice matters because suitability depends on much more than the property’s value.
Choosing a Mortgage Broker in Galashiels
The closest adviser is not necessarily the adviser whose experience best matches your circumstances.
Before deciding who to speak with, consider:
Mortgage experience: Does the adviser regularly deal with the type of borrowing you need?
Property understanding: Can they recognise issues that may arise with older buildings, flats, conservation-area property or homes with unusual features?
Lender access: Which lenders and products can they consider?
Complexity: Do they understand self-employed income, multiple income sources, investment property or specialist finance where relevant?
Fees: What will the advice and arrangement service cost, and when is the fee payable?
Communication: Can appointments be handled in the way that suits you?
Regulation: Does the individual or firm hold the permissions required for the advice you need?
A Mortgage Broker in Galashiels should help you understand the reasoning behind a recommendation, not simply present a product and ask you to accept it.
Galashiels, Selkirkshire and the Scottish Borders
Galashiels has strong historic connections with Selkirkshire, though older geographical records also place it around the traditional Selkirkshire and Roxburghshire boundary. Today the town forms part of the Scottish Borders council area.
For a modern buyer, its significance is more practical.
Galashiels is a substantial Borders centre with local employment, shops and services, a bus interchange and a railway station on the Borders Railway. Nearby Tweedbank extends the area’s rail-connected residential market further east.
That connectivity can attract buyers whose lives stretch beyond one location.
Yet transport links should never replace property due diligence. The street, building, valuation and mortgage still need to work for you individually.
Speak to a Mortgage Broker in Galashiels
A property decision is easier to judge when you ask the important questions before you commit.
Know what you can afford. Understand the Home Report. Check the property. Compare the total mortgage cost. Keep enough room in your finances for life after completion.
Whether you are buying, moving, refinancing, or investing, the right Mortgage Broker in Galashiels can bring those separate decisions together before you decide how to proceed.