
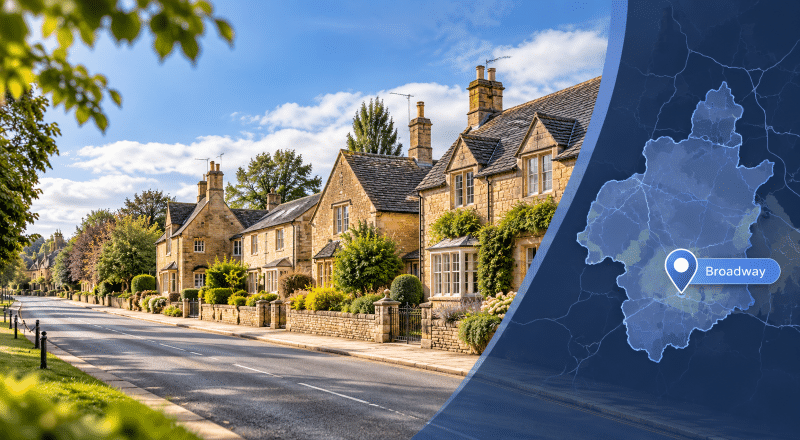
A Mortgage Broker in Broadway can help turn a beautiful property choice into a mortgage decision that works on paper and in real life.
Broadway’s identity is difficult to separate from its housing. Cotswold stone, historic buildings, established homes and its position beneath the Cotswold escarpment give the village much of its character. Yet the features that make a property distinctive can also create extra questions when a lender values it.
The aim is therefore not simply to find somebody nearby. It is to find a mortgage adviser whose experience reflects the borrower, the property, and how the home will actually be used.
At a glance: Mortgage Broker in Broadway
- Broadway sits within the Wychavon district of Worcestershire.
- WR12 identifies Broadway and the surrounding local postcode area.
- Parts of Broadway fall within a designated conservation area.
- The village sits within the Cotswolds National Landscape.
- Historic buildings, Cotswold stone and non-standard features may require closer lender or valuation consideration.
- The average Wychavon house price was £323,000 in July 2026.
- First-time buyers in Wychavon paid £246,000 on average in July 2026.
- Detached homes across Wychavon averaged £484,000.
- Holiday letting and tourism can make intended property use particularly relevant locally.
- Adviser experience may be more useful than simply choosing the geographically closest adviser.
The latest local figures are from the Office for National Statistics and HM Land Registry. They describe Wychavon rather than Broadway alone, so they should provide context rather than be treated as a valuation for an individual property.
Broadway Property Can Require More Than a Standard Checklist
A house is never just its asking price.
For lenders, the property is also mortgage security. Its construction, condition, location, marketability and intended use can therefore influence the application.
That point is particularly relevant in Broadway.
Wychavon District Council identifies a Broadway Conservation Area, while its appraisal highlights the village’s historic layout, architectural character, Cotswold stone buildings and relationship with the surrounding rural landscape.
The Broadway Neighbourhood Plan has also formed part of Wychavon’s development plan since October 2022.
For a buyer, these facts do not mean an older or distinctive Broadway home will be difficult to mortgage. They mean the details matter.
A lender or valuer may need to consider:
- Age and construction of the property
- Cotswold stone walls or roofing
- Listed status
- Significant alterations or extensions
- Condition of the roof and structure
- Access arrangements
- Large plots or outbuildings
- Mixed residential and commercial use
- Evidence of previous building work
- Whether planning or listed-building consent was required
- Whether the property is straightforward to resell
A mortgage adviser cannot replace a surveyor, solicitor or planning specialist, but they can help identify where the property may need a lender with suitable criteria.
Living Inside a Protected Landscape
Broadway sits at the northern end of the Cotswolds National Landscape, where Worcestershire meets one of England’s best-known protected landscapes.
That setting is part of Broadway’s appeal, but the mortgage itself is still decided on practical evidence.
The lender wants to understand two things:
Can the applicant afford the mortgage?
And:
Is the property acceptable security for the loan?
These questions are related, but they are not the same.
A borrower could have an excellent income and deposit yet choose a property that falls outside a lender’s criteria. Equally, a conventional property may still require careful lender selection where income is complex.
Explore the Cotswolds National Landscape
What Could Affect a Mortgage in Broadway?
Several factors can change which lenders or mortgage products suit you.
Self-employed or company income
Broadway and the surrounding area include people whose income may come from businesses, professional work, contracting or several sources.
A lender might assess:
- Salary and dividends
- Company accounts
- Retained profit
- Sole-trader income
- Partnership income
- Bonus or commission
- Rental income
- Investment income
Applicants with these circumstances can compare self-employed mortgage brokers who understand how different lenders assess income evidence.
A mortgage deal approaching its end
Existing Broadway homeowners may need advice without moving house.
When a fixed, tracker or discounted period finishes, the choices might include a new deal with the existing lender or a remortgage elsewhere.
The comparison should look beyond the headline interest rate. Product fees, early repayment charges, remaining balance, loan-to-value and future plans can all change the overall cost.
You can compare mortgage rate ending advisers before the current deal expires.
Holiday Lets and Tourism in Broadway
Broadway’s visitor economy makes intended property use a particularly relevant mortgage question.
Buying a home as a main residence is fundamentally different from buying a property intended for regular short-term paying guests.
Holiday-let lenders may consider factors such as:
- Expected seasonal income
- Property location
- Deposit
- Personal affordability
- Previous landlord experience
- Management arrangements
- Personal use of the property
- Ownership through an individual or limited company
- Evidence supporting projected rental income
A standard residential mortgage should not simply be assumed to permit commercial holiday letting.
Buyers considering this route can compare holiday let mortgage brokers with experience of short-term rental property.
The mortgage adviser should also be told clearly how the property will be used from the start.
Larger Broadway Homes and More Complex Borrowing
Wychavon’s average detached property price was £484,000 in July 2026, compared with an overall district average of £323,000. These are district-level figures, not Broadway-specific valuations.
Higher-value purchases sometimes involve borrowers with less conventional finances.
Examples include:
- Company directors
- Business owners
- Multiple income sources
- Large annual bonuses
- Retained company profits
- Investment income
- Property portfolios
- Significant assets
- Overseas income
- Larger deposits
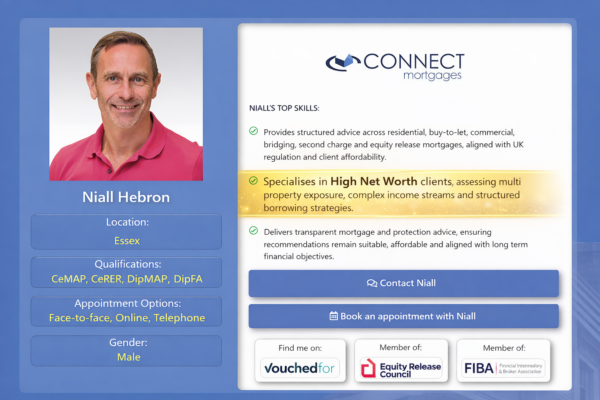
When substantial assets, complex income, or much larger borrowing requirements are involved, borrowers may want to compare high-net-worth mortgage brokers.
The property price alone should not determine whether you need high-net-worth expertise.
What matters is the case’s financial structure.
Finding the Right Mortgage Broker in Broadway
Distance can help, but expertise should normally carry more weight.
Modern mortgage advice can be provided face to face, by telephone or through video appointments. This makes it possible to search beyond a single postcode when a case requires specific experience.
Before choosing an adviser, consider asking:
- Do you regularly deal with properties of this age or construction?
- Have you handled listed or conservation-area homes?
- Which lenders may consider my income type?
- Do you have experience with holiday lets if that is my intended use?
- Can you help before I make a full mortgage application?
- What fees will I pay?
- How are you remunerated?
- What documents should I prepare?
- Are there property issues I should investigate with my solicitor or surveyor first?
The right search is not necessarily about finding the person with the shortest travelling distance.
It is about finding an adviser whose knowledge matches the decision you are trying to make.
Protection Should Sit Beside the Mortgage Conversation
A mortgage can last for decades.
That creates a useful question that has nothing to do with today’s interest rate:
What would happen to the household finances if life changed before the mortgage ended?
Illness, injury, death or a long period away from work can affect the ability to maintain mortgage payments and wider household commitments.
Protection advice may consider areas such as:
- Life insurance
- Critical illness cover
- Income protection
- Family income needs
- Existing workplace benefits
- Savings and emergency funds
- Mortgage balance
- Household expenditure
- Dependants
The right type and amount of cover depends on individual circumstances and budget.
Clients who want to consider the financial commitment alongside their mortgage can speak with Protection Mortgage Brokers through Connect Experts.
Protection should not be treated as an automatic add-on. It should reflect the financial consequences a household would actually face.
Local Knowledge or Specialist Knowledge?
A Mortgage Broker in Broadway should understand that local context can matter, but postcode knowledge alone doesn’t make someone the right adviser.
The stronger match may be an adviser experienced in the specific issue involved.
That could mean:
- First-time buyer lending
- Moving home
- Self-employed income
- A mortgage rate ending
- Holiday lets
- Buy-to-let
- Larger loans
- Complex income
- Older properties
- Protection planning
Connect Experts lets users compare advisers by expertise, location, and personal preferences, rather than being limited to whoever happens to have an office nearby.
Find a Mortgage Broker in Broadway
A mortgage application brings together three separate things: the borrower, the property and the lender’s rules.
Broadway makes that relationship particularly visible.
The character of an older Cotswold property may be exactly what attracts a buyer, yet those same characteristics can make careful lender selection more important. A high income may support the borrowing, but its structure still needs to meet underwriting requirements. A property may make an appealing holiday let, but its intended use needs to fit the mortgage.
Good mortgage advice starts with understanding those differences before you submit an application.
Use the Connect Experts mortgage adviser directory to compare advisers and choose somebody whose experience reflects your circumstances.




