

Mortgage Brokers in County Antrim can help turn a property search into a decision that balances place, affordability and future plans. A home is never simply an address; it becomes part of the way you live, travel, work and manage money for years afterwards.
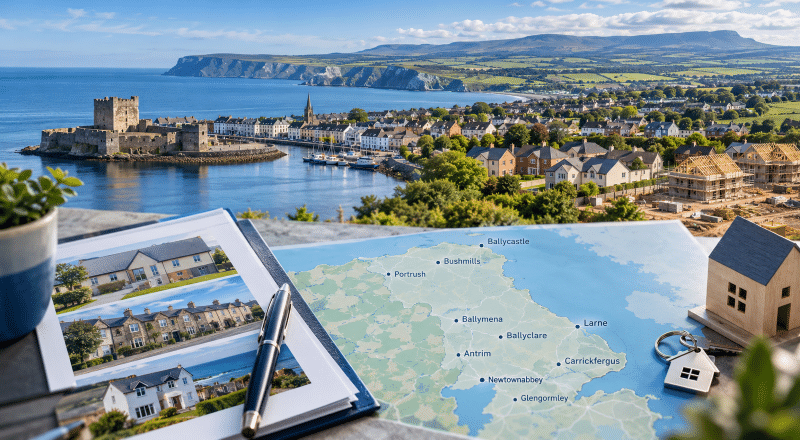
County Antrim gives buyers unusually varied choices. Antrim and Newtownabbey provide access towards Belfast and Belfast International Airport. Ballymena is a substantial regional town. Carrickfergus and Larne combine established communities with coastal settings, while Ballycastle, Bushmills and the North Antrim coast introduce a very different property landscape. Rural villages and countryside homes add another layer.
That variety matters to mortgage lenders.
A modern estate house, rural detached property, coastal cottage, apartment, former agricultural property or home with substantial land may each raise different questions about valuation, construction, marketability and security.
Connect Experts helps you compare advisers by location, mortgage expertise, and personal preferences, rather than assuming the nearest adviser is automatically the right one.
You can also use the Find a Mortgage Adviser by Location service to widen or refine your search.
County Antrim Property Market and Mortgage Considerations
A property market is best understood in context, not reduced to a single average.
That principle matters in County Antrim because the historic county does not correspond to a single modern Local Government District. Official Northern Ireland house-price statistics are published by council area rather than historic county.
The Northern Ireland Statistics and Research Agency reported a standardised average Northern Ireland house price of £202,487 for April to June 2026, an increase of 9.2% over the year. Mid and East Antrim recorded a standardised price of £177,450 during the same quarter.
Those figures provide market context rather than a valuation for an individual home.
Local conditions can differ considerably between:
- suburban locations around Newtownabbey and Glengormley;
- established town housing in Antrim and Ballymena;
- historic property in Carrickfergus;
- port and coastal housing around Larne;
- rural homes outside Ballyclare and Randalstown;
- coastal property around Ballycastle, Bushmills and Portrush.
Evidence also points to ongoing construction activity. In Q2 2026, Antrim and Newtownabbey recorded 210 new dwelling starts, the highest of any Northern Ireland council area that quarter.
For buyers, the lesson is simple: averages may describe a market, but lenders lend against a particular property.
Before applying, consider whether the home has features that may require closer assessment, including substantial acreage, agricultural buildings, unusual construction, private drainage, significant renovation, proximity to commercial premises, coastal exposure or restricted resale demand.
How to Choose a Mortgage Broker in County Antrim
Good advice begins with the right questions.
Before choosing a mortgage broker in County Antrim, consider whether the adviser understands both your financial circumstances and the property’s location.
Useful questions include:
- Does the adviser work with lenders that lend on Northern Ireland property?
- How broad is their lender access?
- Have they handled similar income circumstances before?
- Do they understand rural, coastal or non-standard properties?
- Can they help with a new-build or recently completed property?
- What adviser fees could apply?
- What lender, valuation or product fees could apply?
- How will they communicate with you during underwriting?
- Are appointments available online, by telephone or face to face?
- How will they explain alternative mortgage options and their costs?
You should also check the regulatory position of the adviser or firm through the FCA Financial Services Register.
A broker should never be selected purely because they are nearby.
Distance is measurable. Expertise is more important.
Mortgage Advice Across County Antrim
Every mortgage involves numbers, but they don’t all tell the same story.
Some buyers have straightforward employment income and a conventional property. Others may have multiple income sources, business profits, irregular earnings, or a home that requires closer lender assessment.
A mortgage adviser may be able to help with:
- first-time buyer deposits and affordability;
- residential purchases and home moves;
- remortgaging and existing mortgage reviews;
- self-employed and company-director income;
- contractor or variable earnings;
- buy-to-let and portfolio lending;
- coastal and holiday-let property where appropriate;
- rural homes, land and outbuildings;
- apartments and leasehold property;
- previous credit problems;
- higher-value borrowing;
- specialist property finance.
Northern Ireland also deserves specific lender consideration. Lenders’ geographical criteria differ: for example, Nationwide says it lends on properties in Northern Ireland, while Pepper Money currently says it does not.
That makes lender coverage an important question when choosing an adviser.
For first-time buyers, Connect Experts also provides a dedicated first-time buyer mortgage adviser search.
If communicating in another language would help you understand the mortgage process more clearly, explore Bilingual Mortgage Brokers.
The right mortgage advice should make a complicated decision easier to understand, not merely produce another list of products.
Specialist Mortgage Considerations in County Antrim
Property markets become more complicated when either the borrower or the building sits outside a lender’s standard assumptions.
County Antrim can present both situations.
Specialist considerations could include:
- rural homes with acreage;
- homes with agricultural buildings;
- unusual construction;
- self-build or recently completed properties;
- coastal homes;
- holiday-let proposals;
- portfolio landlords;
- properties above or close to commercial premises;
- self-employed borrowers;
- foreign-currency income;
- applicants working across Northern Ireland and the Republic of Ireland;
- larger mortgages.
Northern Ireland-specific lender criteria can matter here. NatWest, for example, publishes separate Northern Ireland property criteria covering matters including apartments, former Northern Ireland Housing Executive property and self-build homes.
This does not mean one lender is suitable for every borrower. It demonstrates why checking the detail before applying can matter.
Education
A school can influence where a family wants to live, but a property purchase should not be based on assumptions about admission.
Northern Ireland’s Education Authority publishes school information and individual admissions criteria. Parents should check the rules relevant to their preferred schools before committing to a move.
County Antrim covers several education authority areas because modern council boundaries differ from the historic county.
Families comparing locations may therefore want to consider:
- individual school admissions criteria;
- home-to-school travel;
- public transport;
- childcare arrangements;
- after-school costs;
- whether a move changes an existing school journey.
The Education Authority also advises families who expect to move house to provide information about the proposed move during the admissions process where relevant.
Education is not part of a mortgage product, but education-related financial commitments can affect the household budget supporting that mortgage.
Where fee-paying education forms part of the family’s longer-term plan, Education Finance may also be relevant.
Finance
Affordability is rarely explained by salary alone.
A lender may consider your income alongside existing commitments, dependants, credit history, deposit, mortgage term and property.
Income could include:
- basic salary;
- overtime;
- bonuses;
- commission;
- self-employed profits;
- company-director remuneration;
- dividends;
- contract income;
- pension income;
- rental income.
What a lender accepts, and how it calculates that income, can differ.
Likewise, a low headline mortgage rate does not automatically mean the lowest overall cost. Arrangement fees, valuation charges, incentives, early repayment charges and the mortgage term can change the financial outcome.
The purpose of advice is therefore not simply to find the smallest advertised percentage.
It is to find a mortgage structure that fits the borrower, not just the numbers.
Mortgage Protection and Household Security
A mortgage often lasts longer than many other financial commitments.
That makes resilience as important as affordability.
Ask what would happen to the household if income stopped because of illness, injury or death. Consider existing savings, employer benefits, family support and any insurance already in place.
Depending on your circumstances, a protection discussion may include:
- life insurance;
- critical illness cover;
- income protection;
- family income benefit;
- mortgage payment protection.
Protection should be based on individual need and affordability rather than automatically attached to a mortgage.
You can compare Protection Mortgage Brokers for specialist support.
The purpose is not to predict every difficulty life may bring. It is to decide which risks your household would find hardest to absorb.
Later-Life Mortgage Considerations in County Antrim
Later-life borrowing asks a different question from ordinary mortgage affordability.
It is not simply, “Can I borrow this today?”
It is also, “How will this borrowing fit my retirement tomorrow?”
Older homeowners may want to:
- repay an existing mortgage;
- remortgage before retirement;
- move to a smaller home;
- relocate closer to family;
- purchase a retirement property;
- consider a retirement interest-only mortgage;
- investigate equity release.
Equity release is a specialist area and requires regulated advice.
A lifetime mortgage can reduce an estate’s value and may affect entitlement to means-tested benefits. Interest may also compound where payments are not made.
Alternatives should therefore be explored before proceeding.
For homeowners considering this area of financial planning, specialist later-life advice should consider the property, future income, estate-planning objectives and likely long-term housing needs together.
High-Net-Worth
County Antrim should not be described as uniformly high-net-worth.
However, certain larger detached homes, substantial rural properties, coastal residences and borrowers with complex financial arrangements may require higher-value or more specialist lending.
The complexity may come from the borrower rather than the property.
Examples include:
- company owners retaining profits inside a business;
- significant bonus income;
- investment income;
- partnership earnings;
- substantial assets but lower conventional salary;
- multiple properties;
- overseas or foreign-currency income;
- interest-only requirements;
- larger loan sizes.
A standard affordability calculator may not always capture the wider financial position.
Where these circumstances apply, borrowers can explore High-Net-Worth Mortgage Brokers.
The strongest solution is not necessarily the most exclusive lender. It is the lender whose underwriting can properly understand the financial reality.
Find Mortgage Brokers Across County Antrim
Mortgage Broker in Whitehead: Make Your Coastal Move Count
Mortgage Broker in Templepatrick: Smart Advice for a Better Move
Randalstown Mortgage Advice: The Expert Advice Needed
Portrush Mortgage Advice: Make Your Coastal Move Count
Newtownabbey Mortgage Advice: Let the Advice Sink In
Mortgage Broker in Larne: Expert Advice You Can Rely On
Glenarm Mortgage Advice: Secure the Right Fit Before You Commit
Mortgage Broker in Cushendall: Make a Confident Coastal Move
Crumlin Mortgage Advice: Build the Right Plan Before You Move
Mortgage Broker in Carrickfergus: BT38 Expert Local Advice
Mortgage Broker in Bushmills: Finance That Fits the Property
Mortgage Broker in Ballymoney: Plan Beyond the Rate
Ballymena Mortgage Advice: Make Your Property Move Count
Mortgage Broker in Ballyclare: Mortgage Advice is Essential
Ballycastle Mortgage Advice: Make Your Coastal Move Count
Mortgage Broker in Antrim: Think Beyond the Rate
People Also Browse these Counties
A Mortgage Network for Advisers Serving County Antrim
A good adviser network should create opportunity without losing sight of responsibility.
If you are a mortgage broker based in County Antrim, joining the Connect network can help increase your visibility to clients searching for FCA-authorised mortgage advice by location, language and mortgage requirement.
Brokers appearing through Connect Experts can be discovered by clients looking for relevant professional experience rather than simply the nearest adviser.
The objective is simple: help the right client find the right adviser at the point when expertise matters.
Choose the option that suits you best:
Option 1: Schedule a call with our Business Recruitment Manager
Option 2: Complete our contact form
Option 3: Call us

Connect Experts is a mortgage adviser directory and matching platform. We help users find FCA-authorised mortgage advisers. We are not a lender, and the adviser you choose will provide advice based on your circumstances.
Important:
Your home may be repossessed if you do not keep up repayments on your mortgage or any loan secured on it. Some forms of buy-to-let, commercial mortgage and business finance may not be regulated by the Financial Conduct Authority.