Mortgage Broker in Melrose searches often start with a property, but a better question is whether the mortgage fits the home, the borrower, and the years that follow.
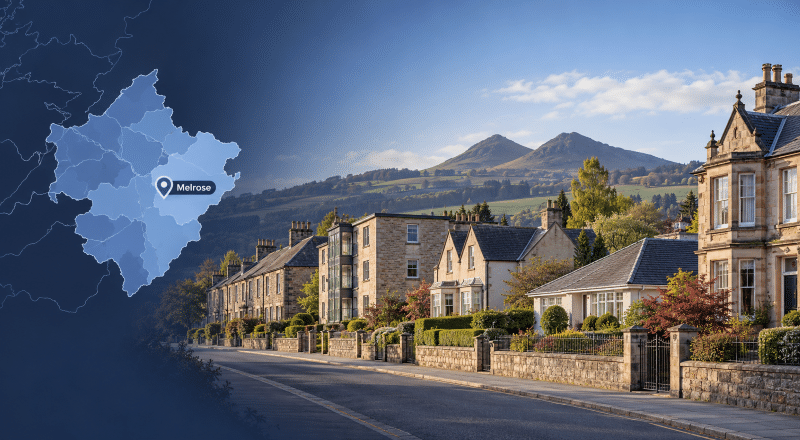
Melrose is not a uniform housing market. Traditional stone homes, properties in its historic centre, detached houses on the edge of town, and homes around nearby Darnick, Gattonside and Newstead can raise very different questions for lenders.
The right advice starts with understanding those differences, not treating the postcode as the whole story.
At a glance: Mortgage Broker in Melrose
- Melrose sits within the TD6 postcode area in the Scottish Borders.
- Its historic core forms part of the Melrose Conservation Area.
- The conservation area contains 69 listed properties.
- Traditional local construction includes sandstone, whinstone, slate and harled finishes.
- The average house price in the Scottish Borders was £195,000 in August 2026.
- First-time buyers in the Scottish Borders paid an average of £150,000 during the same month.
- St Mary’s Preparatory School is based in Melrose, creating a genuine local connection with education-cost planning.
- Property experience and access to suitable lenders may matter more than choosing an adviser purely because they are geographically closest.
What a Mortgage Broker in Melrose Should Consider
A mortgage application is partly about the borrower and partly about the property being offered as security.
That distinction matters particularly in Melrose.
Scottish Borders Council describes the town centre as closely packed and historic, with detached properties more commonly found around its periphery. The conservation area includes sandstone and whinstone buildings, slate roofs, sash-and-case windows and other architectural features that contribute to its character.
These features do not automatically make a property difficult to mortgage. However, an older or unusual home may lead a lender or valuer to consider:
- construction type and materials;
- the property’s condition;
- roof condition and maintenance;
- alterations or extensions;
- listed-building status;
- access and boundaries;
- significant repairs identified by the surveyor;
- whether part of the property has another use.
That makes an accurate property description important from the beginning.
Buying a Home in Melrose: Look Beyond the Asking Price
The latest official figures give useful context, although they cover the wider Scottish Borders rather than Melrose alone.
In August 2026, the provisional average house price across the Scottish Borders was £195,000. First-time buyers paid an average of £150,000, while movers paid an average of £249,000. Detached properties averaged £374,000, compared with £231,000 for semi-detached homes, £189,000 for terraced properties and £112,000 for flats and maisonettes.
A Mortgage Broker in Melrose can therefore help you consider the mortgage in the context of the particular property rather than relying on a broad regional average.
Before committing, compare current borrowing costs on the UK Mortgage Rates page. A headline interest rate is only part of the calculation. Arrangement fees, incentives, loan-to-value, the initial deal period and the cost after that period can all affect overall value.
Understand the Scottish Buying Process
Buying in Scotland follows a different legal process from buying a home in England or Wales.
Most homes marketed for sale require a Home Report. It normally contains a Single Survey and valuation, an Energy Report and a Property Questionnaire. The documents can reveal information about condition, repairs, alterations, energy performance and other matters before an offer is made.
Your solicitor remains responsible for the legal aspects of the purchase, while your mortgage adviser can use relevant property and financial information when assessing possible mortgage routes.
Buyers should also budget for Land and Buildings Transaction Tax (LBTT) rather than Stamp Duty Land Tax. Scotland’s 2026/27 residential bands remain unchanged, and first-time buyer relief increases the nil-rate threshold to £175,000 where the qualifying conditions are met.
First-Time Buyers in Melrose
Your first mortgage should make sense after completion, not merely on the day the lender says yes.
Deposit size, income, existing commitments, and the property valuation will influence what’s available. In Scotland, buyers may also need to think carefully about any difference between the Home Report valuation and the price they intend to offer.
A first-time buyer mortgage adviser can assess affordability, deposit evidence, and lender criteria before you commit to a particular property.
That preparation can be particularly useful when demand drives offers above the valuation, because a mortgage lender will not simply treat every pound over the valuation as additional property value.
Remortgaging a Melrose Home
A mortgage approaching the end of its current rate creates a natural review point.
Do not look only at the interest rate. Consider the remaining balance, loan-to-value, fees, early repayment charges and whether your circumstances have changed.
If your existing deal is approaching its end, a mortgage rate ending adviser can help you compare options, including whether staying with your current lender or moving to another lender makes sense.
Homeowners can also use the UK Mortgage Rates tool to compare current products before discussing their circumstances with an adviser.
Mortgages for Melrose’s Older and Historic Homes
A beautiful building can carry a history that a lender still needs translated into practical information.
Melrose Conservation Area covers the historic core, including many buildings and features that contribute to the town’s distinct character. Scottish Borders Council records 69 listed properties within the amended conservation area.
If you are considering an older home, provide your adviser with the Home Report and any useful information about alterations, repairs, access or unusual construction as early as possible.
A Mortgage Broker in Melrose may then be able to identify lenders whose criteria better suit the property, rather than submitting the case without first considering those details.
For listed buildings, proposed changes may also require listed-building consent, so consider future renovation plans before committing to the purchase.
Buying a Property to Let in or Around Melrose
A rental property is assessed differently from a home you intend to occupy.
The lender may consider expected rental income, property type, borrower experience, loan-to-value and the ownership structure. An existing landlord may therefore need a different approach from somebody buying their first rental property.
Depending on your plans, relevant expertise may include:
- Portfolio landlord mortgage advice if you already own several rental properties.
- First-time landlord mortgage advice when buying your first investment property.
- Limited company buy-to-let advice where the proposed purchase will be made through a company.
- HMO mortgage advice if the proposed property and letting arrangement meet HMO requirements.
The appropriate route depends on the property, tenancy, ownership structure and your wider financial position.
Education Finance and Melrose Families
Melrose has a genuine independent-school connection, not one added merely for SEO.
St Mary’s Preparatory School is based at Abbey Park in Melrose and serves children aged 2 to 13.
For homeowners considering how school costs fit alongside their mortgage and wider household commitments, Education Finance may be relevant.
Possible routes can include a remortgage, further advance, second-charge mortgage or other suitable borrowing arrangement. They are not automatically appropriate simply because equity exists in a property. Affordability, interest costs, fees and the repayment plan still need careful assessment.
Protection Advice Should Sit Beside the Mortgage
A mortgage establishes a long-term financial commitment. Protection asks what happens to that commitment when life changes unexpectedly.
A Mortgage Broker in Melrose may therefore discuss the mortgage alongside suitable protection advice.
Depending on your circumstances, an adviser with the relevant permissions may discuss areas such as life insurance, critical illness cover, income protection and other suitable protection arrangements.
The aim is not to add insurance automatically. It is to understand which financial risks exist and whether appropriate cover could help protect the household and mortgage.
Later-Life Borrowing and Equity Release in Selkirkshire
For older homeowners, the right answer may not be a conventional residential remortgage.
Later-life borrowing can involve different products, eligibility rules, interest structures and long-term effects on the property and estate.
If you are considering releasing money from your home, explore Equity Release Advisers in Selkirkshire through Connect Lifetime.
Equity release can reduce the value of your estate and may affect entitlement to means-tested benefits. It should be considered through specialist advice based on your circumstances and long-term plans.
Choosing Mortgage Advice for Melrose
The nearest adviser is not automatically the adviser best suited to your circumstances.
What matters is whether the adviser understands the type of borrowing you need and can properly assess the property, income, and lender criteria.
When choosing an adviser, consider:
- experience with your mortgage type;
- knowledge of older or non-standard properties where relevant;
- access to suitable lenders;
- how fees will be charged;
- telephone, online or face-to-face appointment options;
- whether the adviser holds the permissions required for the advice you need.
In some cases, specialist knowledge matters more than physical distance.
Start With a Mortgage Broker in Melrose
A good mortgage decision should leave room for the life that comes after completion.
Whether you are buying your first home, moving within the Borders, remortgaging an established property or considering a rental investment, the first task is to understand what your circumstances require.
Use Search Connect Experts to find an adviser whose experience matches your mortgage needs, property, and financial position.
Find a mortgage adviser and start your search.