Mortgage Broker in Ettrick searches often start with a rate, but in this part of Selkirkshire, the property itself can matter as much as the borrowing. A mortgage is a promise about the future, while a rural home is also a commitment to its land, access, services and surroundings.
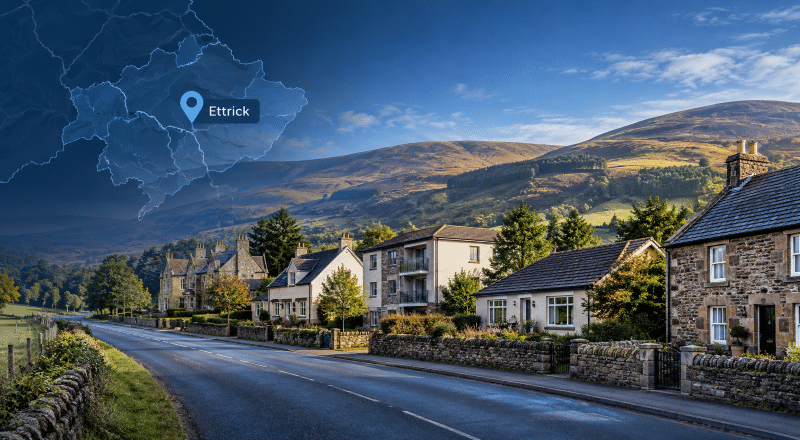
Ettrick, also known around Hopehouse, lies in the upland Ettrick Valley within the Scottish Borders and historic Selkirkshire. Ettrick addresses include the TD7 5JA postcode, while the B709 runs through the valley towards Ettrickbridge and wider routes towards Selkirk. Scottish Borders Council describes Ettrick as approximately 17 miles south-west of Selkirk.
At a glance: Mortgage Broker in Ettrick
- Ettrick is a rural TD7 community, around 17 miles south-west of Selkirk by road.
- The B709 is a key valley route, so access and road conditions can matter when assessing rural property.
- Ettrick Primary School closed in December 2019, with its former catchment rezoned to Kirkhope Primary School in Ettrickbridge.
- The average Scottish Borders house price was £195,000 in August 2026, while first-time buyers paid £150,000 on average.
- Detached homes across the Scottish Borders averaged £374,000 in August 2026.
- River flooding from Ettrick Water and flooding affecting road access are recognised considerations in the wider valley.
- Some rural Scottish homes use private water or drainage, so buyers should confirm services rather than assume mains connections.
Rural property needs a fuller description
A Mortgage Broker in Ettrick can organise the borrowing, but the valuation and legal work still need an accurate description of the home. A conventional house may be assessed differently from a cottage with acreage, outbuildings, a private track or non-standard services.
In Scotland, the seller normally provides a Home Report containing a single survey and valuation, a property questionnaire, and an energy report. Buyers should read it alongside their solicitor’s checks, particularly where repairs, alterations or unusual property features are recorded.
For a rural Ettrick purchase, establish the boundaries, access rights, outbuildings, any business or agricultural use, and whether water and drainage are private. Around 3% of Scotland’s population receives drinking water from private supplies, which are particularly common in rural and remote areas. SEPA also provides a facility for checking whether private sewage treatment systems are registered.
Flood risk deserves the same care. Scottish Borders flood planning identifies the Ettrick Water as the main river-flooding source in the wider Selkirk and Ettrick Valley area and notes that road flooding can affect access. The SEPA flood maps are useful for area-level screening, but SEPA makes clear that they do not assess an individual property’s specific flood risk.
Compare the mortgage after defining the property
A Mortgage Broker in Ettrick should understand both the borrower and the security being offered to the lender. Before comparing products, be clear about your deposit, income, commitments, intended use and any property features a valuer may need to consider.
You can compare current UK mortgage rates as a starting point, including indicative repayments and lender fees. A displayed product does not confirm eligibility. Lenders still assess affordability, credit history, deposit, the property and their own lending criteria.
If your existing deal is nearing its end, a mortgage-rate-ending adviser can help you compare options, such as staying with your current lender or remortgaging elsewhere.
Arrangement fees, early repayment charges, valuation costs, and the remaining mortgage term can all affect whether a lower headline rate offers better overall value.
When the property will produce income
Ettrick’s rural setting may also suit buyers considering a let or property investment. The right finance should follow the property’s intended use rather than trying to make the property fit a particular mortgage.
Someone entering the rental market can look for a first-time landlord mortgage adviser, while landlords with several properties may benefit from a portfolio landlord mortgage adviser.
Where a company will own the property, limited company buy-to-let mortgage advice may be more relevant.
If refurbishment is central to the purchase, short-term buy-to-let bridging finance advice may sometimes be considered before longer-term borrowing, subject to costs, the proposed exit strategy and lender criteria.
If land, a change of use, or a development project is central to the transaction, a development finance adviser may be more appropriate than standard residential borrowing.
Some buy-to-let, commercial and business finance is not regulated by the Financial Conduct Authority.
Protection should sit beside the mortgage
When a Mortgage Broker in Ettrick helps you plan a long-term mortgage, it is also sensible to consider what happens if life does not follow the original financial plan.
Illness, injury, loss of income or death can change a household’s ability to meet mortgage payments. Protection advice can include life insurance, critical illness cover and income protection, depending on individual circumstances.
Connect Experts can help you find protection mortgage brokers who can review cover alongside your mortgage commitment.
Premiums, exclusions, waiting periods, benefit limits and claim conditions vary between policies. Protection should therefore reflect your needs and budget rather than being treated as an automatic addition to a mortgage.
Later-life borrowing in Selkirkshire
For older homeowners, property value may open different financial choices, but releasing housing wealth is not simply another type of remortgage.
Anyone considering equity release should receive regulated later-life advice and consider alternatives as part of that process. Equity release can reduce an estate’s value, may affect entitlement to means-tested benefits, and can add interest to the borrowing over time.
For specialist support, see Equity Release Advisers in Selkirkshire on Connect Lifetime.
The advice process should consider long-term plans, property eligibility, alternatives and the possible effect on family finances before a recommendation is made.
Make the application describe the real home
Choosing a Mortgage Broker in Ettrick isn’t about finding the adviser closest to you.
The more useful question is whether the adviser understands your borrowing needs and recognises when a rural property requires additional lender, valuation or legal attention.
Prepare the application around the real property: its construction, access, services, land, outbuildings, intended use and known environmental issues. Then compare the mortgage on the same basis.
That order matters. A rate can look attractive on a screen, but the mortgage still has to work for the borrower and the property standing behind it.
Connect Experts helps users search for advisers and specialist support. Information on this page is general and does not constitute personal mortgage advice. Adviser availability, lender criteria, product rates, fees and eligibility can change.