
A Mortgage Broker in Manton can help you recognise that finding the right home and choosing the right mortgage are two different decisions. One depends on where you want to live. The other determines how comfortably you can afford to remain there.
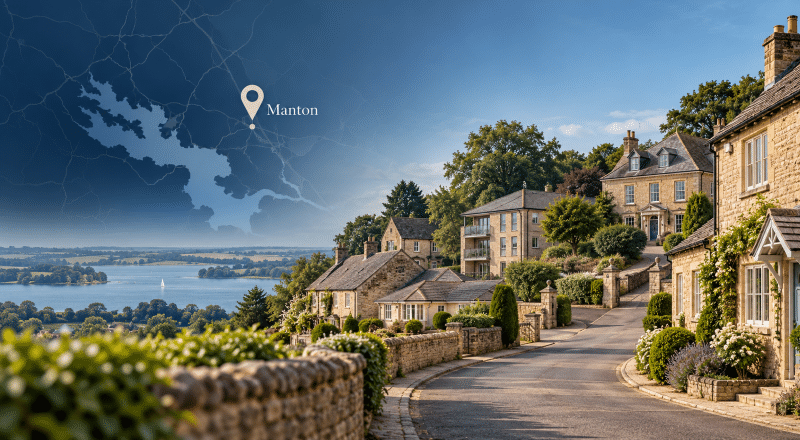
Manton is a small Rutland village near the southern shore of Rutland Water, with historic properties, rural surroundings and access to Oakham and Uppingham.
For buyers, these characteristics can create opportunities, but they can also introduce mortgage considerations that are easy to overlook.
A traditional stone cottage, a detached family home, and a property with land may each require a different approach to choosing a lender.
Connect Experts helps you find mortgage advisers who understand your borrowing needs, whether you are moving to Manton, buying your first home, reviewing an existing mortgage, or financing an investment.
At a glance: Mortgage Broker in Manton
- Location: Manton is a Rutland village within the LE15 postcode area, close to Rutland Water.
- Property character: The village includes traditional stone cottages, listed buildings and more conventional residential properties.
- Historic buildings: Several properties are listed, including The Forge on Stocks Hill. Manton itself is not a designated conservation area.
- Local mortgage considerations: Construction, property condition, valuation and any additional land may influence lender suitability.
- Rutland average house price: £299,000 in July 2026, down 6.5% annually.
- First-time buyers: Paid an average of £233,000 across Rutland in July 2026.
- Detached homes: Averaged £431,000 across Rutland, illustrating the county’s range of property values.
- Education: Independent schooling is available in nearby Oakham and Uppingham.
- Adviser selection: Experience with rural and older properties may be particularly useful.
Property figures are provisional county-level statistics, not Manton-specific sale prices.
Sources: Office for National Statistics, July 2026 a
Why Manton Properties Can Require a Different Mortgage Approach
Not every property presents the same risk to a lender.
Manton’s historic character is part of its appeal, yet some older properties can require more detailed assessment before a mortgage offer is issued.
The village includes properties dating back several centuries. Historic England records The Forge on Stocks Hill as a Grade II listed building with seventeenth-century origins.
A Mortgage Broker in Manton can help identify lenders whose criteria suit the property and the applicant.
What might a lender want to know?
For traditional or unusual properties, lenders may consider:
- Whether the property uses standard or non-standard construction.
- The condition and expected lifespan of its roof.
- Evidence of structural movement, damp or necessary repairs.
- Whether the property is listed and subject to restrictions.
- The availability of comparable local sales for valuation.
Whether substantial outbuildings, land or separate accommodation affect the security.
A lender’s valuation is not the same as a full building survey. Buyers considering older properties may benefit from an appropriately qualified surveyor before committing to a purchase.
For further information, visit Rutland County Council’s guidance on listed buildings.
Understanding Mortgage Affordability in Rutland
A village setting can influence where someone wants to live. It does not, however, determine how much a lender will allow them to borrow.
According to the Office for National Statistics, Rutland’s average property price was £299,000 in July 2026.
The figures reveal an important difference between property types:
| Property type | Rutland average, July 2026 |
|---|---|
| Detached | £431,000 |
| Semi-detached | £279,000 |
| Terraced | £229,000 |
| Flats and maisonettes | £129,000 |
Source: ONS Housing Prices in Rutland. Provisional county averages, not Manton asking prices.
It is whether the monthly repayments remain affordable alongside household spending, savings commitments and potential maintenance costs.
A mortgage adviser may assess your earnings, deposit, existing credit commitments and anticipated costs before recommending a suitable borrowing structure.
Buying Your First Home in Manton
A first home should create independence, not financial pressure that limits every other part of life.
First-time buyers considering Manton should understand affordability before viewing properties to avoid disappointment later.
Rutland’s average first-time buyer purchase price was £233,000 in July 2026, although this does not represent the price of an individual home in Manton.
You may need to consider the difference between an agreement in principle and a formal mortgage offer, how gifted deposits are assessed, and whether the property itself meets a lender’s criteria.
An agreement in principle helps you set a budget, but it does not guarantee mortgage approval.
Moving to Manton: Think Beyond the Purchase Price
Manton appeals to people who value village surroundings and access to Rutland’s countryside.
However, choosing a home also involves practical questions about commuting, local services, long-term maintenance and family commitments.
Someone moving from a modern property to an older cottage may find that ownership costs differ, even if their monthly mortgage repayment is similar.
A larger rural home might require more for heating, insurance, repairs, and ongoing upkeep.
Mortgage advice should account for these commitments rather than focus solely on the maximum amount a lender may offer.
For those relocating from another area, an adviser can also explain how an existing mortgage might be ported and whether additional borrowing is possible.
Lenders must approve porting and complete affordability checks.
Independent Schooling and Family Mortgage Planning
Education can be an important consideration for families moving into Rutland.
Manton is within reach of two established independent schools: Oakham School and Uppingham School.
For households considering independent education, the mortgage decision should be assessed alongside existing or anticipated school fees.
Lenders may factor in regular school fees when assessing affordability, depending on their policies.
Families should consider whether their proposed mortgage repayments would remain sustainable as education costs and other commitments change.
When specialist financial planning is appropriate, Connect Mortgages Education Finance can help you discuss mortgage affordability alongside wider family financial commitments.
The goal is not necessarily to maximise borrowing. The goal is to balance housing costs, education, and future financial flexibility.
Remortgaging in Manton: Review Your Options Before Your Rate Ends
A mortgage that suited your circumstances several years ago may no longer suit you today.
Changes in interest rates, household income, property value and personal commitments can all affect your next mortgage decision.
If your existing fixed-rate mortgage is nearing its end, reviewing your options early may help you avoid moving onto your lender’s standard variable rate unnecessarily.
A Mortgage Broker in Manton can help homeowners compare options, including whether to stay with their current lender or remortgage elsewhere.
Important considerations include your remaining mortgage balance, current property valuation, available equity, product fees and any early repayment charges.
Homeowners approaching the end of their existing deal can find a specialist through our mortgage rate ending adviser search.
The best decision is not necessarily the mortgage with the lowest advertised interest rate. It is the arrangement that offers an appropriate balance of cost, flexibility and suitability.
Buy-to-Let Mortgages in Manton and the Surrounding Area
The financial considerations for an investment property differ from those for a family home.
For landlords considering Manton or nearby locations such as Oakham and Uppingham, mortgage approval may depend on rental income, property characteristics, deposit size, and the applicant’s wider financial circumstances.
Rutland’s average monthly private rent was £961 in August 2026, according to the ONS. This is a county-wide figure and should not be treated as an achievable rental income for an individual Manton property.
Depending on the investment strategy, Connect Experts provides access to advisers specialising in:
- first-time landlord mortgages for those purchasing their first rental property.
- portfolio landlord mortgages for investors managing multiple properties.
- limited company buy-to-let mortgages for qualifying property investments through a company.
Applicants considering holiday accommodation near Rutland Water should also establish whether the proposed use meets residential, holiday-let or other specialist lender criteria.
Property use, local planning requirements and anticipated rental income can affect the finance available.
Some forms of buy-to-let mortgage are not regulated by the FCA.
Protection Advice: Looking After More Than Your Mortgage
A mortgage is a financial commitment based partly on your ability to keep up with repayments.
But what happens if that ability changes?
Illness, an accident or the death of an income earner can affect a household’s financial security.
Protection advice is therefore an important part of considering the responsibilities that come with a mortgage.
Depending on individual circumstances, an appropriately authorised protection adviser may discuss life insurance, critical illness cover, income protection and other relevant policies.
These products serve different purposes and should not be treated as interchangeable.
For homeowners with dependants or substantial mortgage commitments, understanding the differences may be particularly important.
Connect Experts helps clients find mortgage protection advisers who can review individual needs and explain suitable options.
Protection isn’t meant to cover every possible event. It is to consider which financial risks could most affect your household and whether appropriate cover is available.
Equity Release and Later-Life Mortgage Advice in Rutland
For some homeowners, the most important mortgage question arises much later in life.
A property may have increased in value over many years, but accessing that value requires careful consideration.
Homeowners aged 55 or over may be eligible to explore lifetime mortgages, depending on their circumstances and the property.
A lifetime mortgage allows eligible homeowners to borrow against their property while retaining ownership, subject to the product’s terms.
However, interest can accumulate over time, reducing the remaining equity and potentially affecting future inheritance.
Before considering equity release, homeowners should also examine alternatives, including conventional remortgaging, retirement interest-only mortgages and downsizing where appropriate.
Connect Lifetime Mortgages provides specialist guidance through its equity release advisers in Rutland page.
This is particularly relevant for homeowners who want to understand how their property wealth might support retirement without overlooking the long-term financial implications.
Equity release can reduce the value of your estate and may affect entitlement to means-tested benefits. Specialist regulated advice and independent legal advice are required before proceeding.
Finding the Right Mortgage Adviser for Your Circumstances
The closest adviser is not automatically the most suitable adviser.
For some borrowers, local familiarity may be valuable. For others, specialist experience with an unusual property or complicated income structure may matter more.
A Mortgage Broker in Manton should be selected according to the type of advice you need, the adviser’s relevant experience and their ability to explain your options clearly.
Through Connect Experts, you can search for advisers by location, mortgage expertise, language, and other preferences.
Before selecting an adviser, consider their experience with your mortgage requirements, applicable fees, regulatory permissions and whether they offer advice from a restricted or broader lender panel.
You can independently verify the firm’s regulatory status using the Financial Conduct Authority Financial Services Register.
Specialist Mortgage and Property Finance
Some Manton property purchases may require finance beyond a standard residential mortgage.
For example, someone buying a property that needs significant refurbishment may find that conventional lenders will not accept it in its current condition.
An investor acquiring a building for redevelopment may need an entirely different lending structure.
Depending on the project, relevant specialist advice could include:
| Finance requirement | Find an appropriate adviser |
|---|---|
| Short-term funding for commercial property | Commercial bridging loan advisers |
| Property conversion or development | Development finance advisers |
| Premises for an owner-operated business | Owner-occupied commercial mortgage advisers |
| Commercial investment property | Commercial investment property finance advisers |
These specialist products are not appropriate for every applicant. Bridging and development finance can involve higher costs, shorter repayment periods, and significant risks if an exit strategy fails.
Find Mortgage Advice in Manton That Fits Your Plans
A home is more than an asset on a lender’s balance sheet.
It represents security, independence and the opportunity to build a future in a place that matters to you.
Yet the mortgage supporting that home should remain a considered financial decision.
Whether you are buying a traditional Rutland cottage, moving into a larger family property, reviewing an existing mortgage or exploring specialist finance, understanding your choices can help you make a more informed commitment.
A Mortgage Broker in Manton can help you examine mortgage affordability, lender criteria, borrowing costs and your longer-term objectives.
Connect Experts makes it easier to find an adviser whose experience matches your circumstances.
Find a mortgage adviser covering Manton and take the next step with greater clarity.
Find a Mortgage Adviser by Location




