
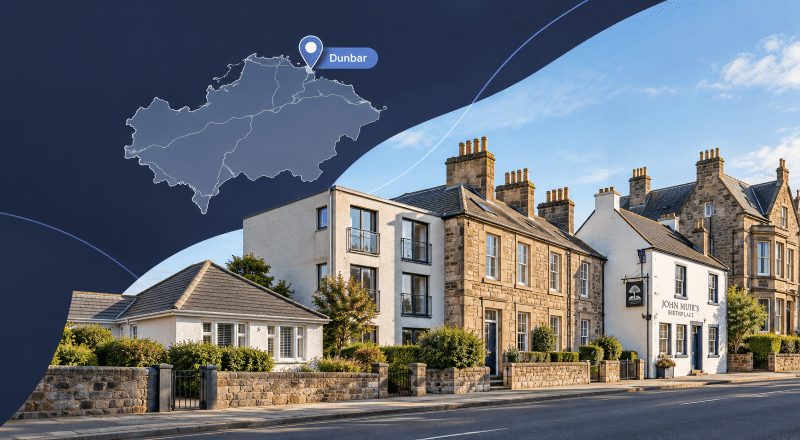
At a glance: Mortgage Broker in Dunbar
- Dunbar combines historic town-centre property, coastal homes and modern developments.
- Dunbar Burgh and Belhaven are both designated conservation areas.
- Traditional stone construction, listed buildings and older properties may need more detailed lender consideration.
- East Lothian’s average house price was £283,000 in July 2026.
- First-time buyers across East Lothian paid £220,000 on average in July 2026.
- Dunbar sits on the East Coast Main Line and has direct rail connections towards Edinburgh.
- Belhaven Hill School gives Dunbar a genuine independent-school connection.
- The main Dunbar postcode area is EH42.
A home is rarely chosen from numbers alone.
For some buyers, Dunbar’s appeal may be its coast. For others, it may be the rail connection, established community, schools, or the chance to live beyond Edinburgh while staying connected to it.
A Mortgage Broker in Dunbar can look beyond the asking price and consider how the property, deposit, income and wider plans fit together.
This is particularly useful in a town where housing ranges from traditional stone properties and flats around the historic centre to newer family homes in expanding residential developments.
Different Dunbar homes can raise different mortgage questions
Two properties in the same town can produce very different lender decisions.
An older home in Dunbar’s historic areas may raise questions about construction, alterations, valuation, or condition. More modern properties may involve different considerations, including incentives on new-build purchases or lender loan-to-value restrictions.
East Lothian Council identifies both Dunbar Burgh and Dunbar Belhaven as conservation areas. That doesn’t mean buyers can’t get a mortgage, but it does make sense to understand the property before committing to finance.
A Mortgage Broker in Dunbar can assess borrowing alongside the type of property you’re buying, rather than treating every EH42 application the same way.
This may include looking at:
- Residential purchases.
- First-time buyer mortgages.
- Moving home.
- Remortgaging.
- Self-employed income.
- Complex or multiple income sources.
- Buy-to-let.
- Limited company borrowing.
- Bridging requirements.
- Commercial property finance.
The right starting point is not simply, “What rate can I get?”
It is, “What does this particular move require?”
Buying your first home in Dunbar
For a first-time buyer, the deposit is only one part of the calculation.
Lenders will also consider income, regular commitments, credit history, and the type of property you’re buying. Buyers should leave room in their plans for legal costs, valuation requirements, moving expenses and the unexpected costs that can follow a purchase.
East Lothian’s average first-time buyer price was £220,000 in July 2026. That figure is useful context, but individual properties in Dunbar can sit well above or below a local authority average.
Working with a Mortgage Broker in Dunbar can help you compare the numbers that matter to your own circumstances rather than relying on a headline regional figure.
Dunbar, Edinburgh and the commuter mortgage decision
Dunbar has a useful geographical advantage.
The A1 provides the principal road link towards Edinburgh, while Dunbar railway station sits on the East Coast Main Line. East Lothian Council says Edinburgh is about a 30-minute train ride from the town.
That can widen the search area for people whose income is tied to Edinburgh but who prefer to live further along the East Lothian coast.
However, where you work and where you live are only part of a lender’s assessment.
Hybrid working, overtime, bonuses, commission and variable income may all need to be evidenced differently. Commuting costs can also count as household expenditure.
This is where advice becomes less about geography and more about understanding the household’s overall finances.
When your current mortgage rate is coming to an end
Don’t assume a remortgage should start with the idea that changing lenders is always the answer.
Your existing lender may offer a suitable product transfer. Another lender may offer a better option. Similarly, changes in income, property value, loan size, or future plans may mean staying put deserves serious consideration.
If your existing deal is approaching its end date, an adviser can review your options before you move automatically onto a lender’s standard variable rate.
You can also search for a mortgage rate ending adviser where your priority is reviewing an existing mortgage deal.
A Mortgage Broker in Dunbar can compare that decision with your wider plans, including whether you intend to move, borrow more, reduce the balance or change the mortgage term.
Buy-to-let and property investment around Dunbar
Dunbar’s housing market is not limited to owner-occupiers.
Landlords may be considering a first investment, adding to an existing portfolio or purchasing through a limited company.
The borrowing structure matters because lender criteria can change by property type, rental calculation, ownership structure, and the landlord’s wider portfolio.
Depending on your circumstances, you can search specifically for a:
Where the property is an HMO rather than a conventional single-household let, more specialist lender criteria can apply. In that situation, you can search for an HMO mortgage adviser.
The FCA does not regulate most buy-to-let mortgages.
Independent education and mortgage planning in Dunbar
Dunbar has a genuine independent-school connection, not just proximity.
Belhaven Hill School is based on Belhaven Road in EH42 and provides co-educational day and boarding education for children aged 4 to 13.
Families considering private education may therefore need to think about housing and education costs together.
School fees are an ongoing household commitment. A lender may consider those costs when assessing affordability, even where the applicants have substantial income or equity.
Connect Mortgages provides guidance on education finance for private school fees, including how eligible homeowners might consider a further advance, remortgage, second charge or other suitable funding structure.
Property equity does not automatically mean additional borrowing will be affordable. Any secured borrowing should be considered alongside school fees, household costs, emergency savings and longer-term plans.
Protecting the mortgage as well as arranging it
Getting the mortgage is only one part of owning a home.
It is also worth considering what would happen if illness, injury or death affected the household income used to support the mortgage.
Protection requirements differ from one household to another. Depending on circumstances, a discussion might include life insurance, critical illness cover, income protection or other appropriate policies.
A Mortgage Broker in Dunbar may therefore be only one part of the conversation. Clients who want to explore the wider financial consequences of their mortgage can also search for a protection mortgage broker.
Protection policies have terms, conditions and exclusions, and eligibility and cost depend on individual circumstances.
When short-term finance forms part of the plan
Sometimes a conventional mortgage cannot complete the whole journey.
A buyer may need short-term funding because of timing, refurbishment work, a chain problem or the need to complete before longer-term finance becomes available.
Where appropriate, you can search for advisers experienced in short-term bridging loans.
Property developers can also search for a development finance adviser where funding relates to a development rather than a standard residential purchase.
Bridging finance can be more expensive than conventional mortgage borrowing, so the exit strategy is particularly important.
Mortgage advice should start with the destination
A mortgage is a financial commitment, but people rarely move home because they want a mortgage.
They move because they want something on the other side.
That might be more space, a different pace of life, access to the coast, proximity to school, a manageable commute or simply a home that suits the next stage of life.
Good mortgage advice should keep that destination in sight.
Your adviser can consider the lender, borrowing structure, and property, while also asking what you expect the mortgage to let you do next.
If Dunbar is part of that next chapter, search for a Mortgage Broker in Dunbar who has the permissions and experience appropriate to your circumstances.




