
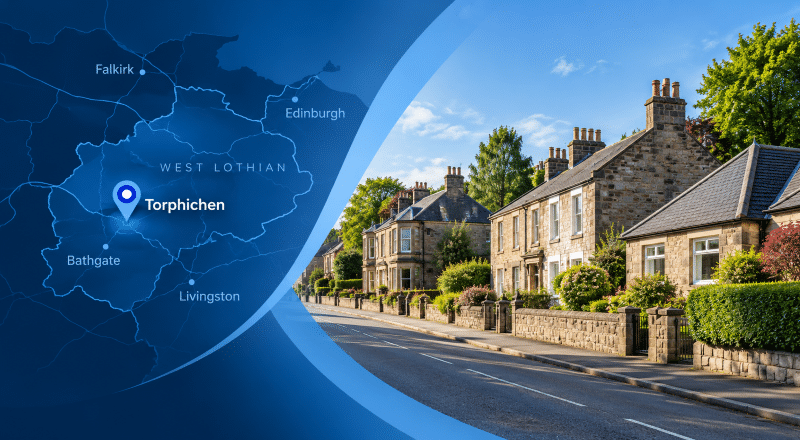
Finding a Mortgage Broker in Torphichen is about more than comparing rates; it is about matching a long-term financial commitment to a place with its own housing character. A home is tangible, but the future is not. Good mortgage planning therefore means testing today’s borrowing against tomorrow’s possibilities, not simply asking what a lender will offer now.
Torphichen sits in north-west West Lothian between Bathgate and Linlithgow. Its village setting, historic buildings and varied housing mean the property itself can sometimes require as much attention as the applicant’s income.
At a glance: Mortgage Broker in Torphichen
- Torphichen is around two miles north-north-west of Bathgate and approximately three miles south-south-west of Linlithgow.
- The village has a designated conservation area, with additional planning controls applying to certain alterations.
- Traditional stone homes, individually designed properties, and rural-edge housing may require closer attention to construction, condition, and valuation.
- West Lothian’s average house price was approximately £227,000 in July 2026, up 2.3% from a year earlier.
- Recent Torphichen sold-price data indicates a small market in which detached properties can transact materially above the wider West Lothian average.
- Bathgate and Linlithgow provide nearby rail connections for people travelling beyond the village.
- Adviser experience with your income, property and lender criteria can matter more than physical distance.
Mortgages in Torphichen and the Local Housing Market
Torphichen has characteristics that set it apart from larger settlements elsewhere in West Lothian.
West Lothian Council describes the village as approximately two miles from Bathgate town centre, three miles from Linlithgow and eight miles from Livingston. Major roads are nearby, while rail services are available from Bathgate and Linlithgow.
That combination can appeal to buyers looking for a village environment without becoming disconnected from larger employment and transport centres.
The housing stock is equally important for mortgage purposes.
Torphichen includes traditional stone buildings, established houses and newer homes. The village is also covered by a designated conservation area. West Lothian Council states that works which might normally fall within permitted-development rights can require planning permission in a conservation area, and Torphichen is also subject to an Article 4 Direction.
For a lender, the central questions remain whether the property provides acceptable security and whether the applicant can afford the borrowing. However, valuation, construction, condition, alterations and planning history may need closer consideration when a home differs from standard modern housing.
What Do Torphichen House Prices Tell Buyers?
The wider West Lothian market provides a useful benchmark.
The Office for National Statistics reported a provisional average property value of £227,000 in July 2026, compared with approximately £222,000 a year earlier. That represented annual growth of 2.3%.
Torphichen’s individual market can look very different.
Rightmove’s recorded sales showed an overall average of approximately £452,167 during the previous year, with detached properties averaging about £627,500.
Those numbers need context. Torphichen is a relatively small market, so a limited number of substantial detached sales can significantly affect an annual average. They should therefore not be treated as an estimate of what a particular home is worth.
For mortgage purposes, the lender’s own valuation remains critical.
What Lenders May Assess for a Torphichen Mortgage
A Mortgage Broker in Torphichen can help you understand how lenders are likely to assess both you and the property before you submit an application.
Affordability remains central, but lender criteria can differ significantly.
An adviser may consider:
- salary and contractual income;
- overtime, commission and bonuses;
- self-employed profits or drawings;
- company director salary and dividends;
- deposit size;
- loan-to-value;
- existing credit commitments;
- credit history;
- mortgage term;
- age at the end of the proposed term;
- property construction;
- valuation findings;
- significant alterations or extensions;
- the source of a gifted deposit where relevant.
Property type matters more with older or individually designed homes.
A lender may be perfectly comfortable with one construction type while another lender applies restrictions. Establishing this before you go too far can reduce the risk of choosing a mortgage based purely on rate and later discovering the property doesn’t meet the lender’s requirements.
Buying an Older Home in Torphichen
Historic character can make a property attractive, but character and mortgageability are different questions.
Some older homes may have:
- traditional stone construction;
- previous extensions;
- non-standard roof materials;
- historic alterations;
- listed or conservation considerations;
- outbuildings or larger plots;
- private drainage or other rural features.
None of these automatically prevents mortgage lending.
They do mean that lender selection may require more care.
Torphichen’s conservation status is especially relevant when alterations have taken place. Buyers should normally ensure that their solicitor establishes whether relevant permissions and consents were obtained where required.
West Lothian Council provides detailed information about the Torphichen Conservation Area and the planning controls that apply.
First-Time Buyers in Torphichen
First-time buyers considering Torphichen may also be comparing homes in Bathgate, Linlithgow, Armadale or elsewhere in West Lothian.
Purchase price is only one part of that decision.
A sensible affordability assessment can also include:
- deposit;
- mortgage repayments;
- buildings insurance;
- council tax;
- commuting costs;
- maintenance;
- surveys;
- legal expenses;
- likely repairs to an older property.
A larger deposit can reduce loan-to-value and may provide access to a broader range of mortgage products, although suitability depends on individual circumstances.
Torphichen Primary School is located within the village, but West Lothian Council specifically advises buyers not to rely solely on published catchment maps when making property decisions and to verify placement information separately.
That makes school catchment a useful consideration, not something buyers should assume from an address alone.
Moving Home to Torphichen
Existing homeowners may have additional decisions to make.
If you already have a mortgage, you might be able to:
- port the existing product;
- increase borrowing with your current lender;
- replace the mortgage with a new lender;
- repay the existing arrangement and take a different mortgage.
Porting a mortgage does not usually mean the borrowing transfers automatically.
The lender will normally reassess affordability, credit circumstances and the new property. If you need extra borrowing, the lender may offer it on different terms than your existing product.
The key comparison is the whole borrowing arrangement, not simply whether you can keep your old rate.
Remortgaging a Home in Torphichen
Remortgaging can also benefit from preparation.
Property values may have changed since the mortgage was originally arranged, potentially affecting loan-to-value. Household income, employment, debts, and monthly expenditure may also have changed.
Homeowners approaching the end of a fixed or discounted period can review:
- their current lender’s product-transfer options;
- remortgage products elsewhere;
- arrangement fees;
- early repayment charges;
- valuation requirements;
- repayment term;
- whether additional borrowing is needed.
The mortgage with the lowest advertised rate is not necessarily the lowest-cost option once you include fees and other terms.
Finding the Right Mortgage Adviser
Choosing a Mortgage Broker in Torphichen should begin with your circumstances rather than postcode alone.
Connect Experts lets you compare advisers by location, mortgage requirements, and other preferences. The directory currently lets users filter advisers according to factors including location, language and specialism.
A local adviser can be useful where you value knowledge of the surrounding market. However, mortgage advice can also be delivered remotely, so experience with your particular circumstances may matter more than geographical proximity.
Before choosing an adviser, consider asking:
- Do you regularly deal with my type of mortgage?
- How do lenders assess my particular income?
- Have you handled older or unusual properties?
- Which lender restrictions could affect the property?
- What adviser fees apply?
- When would those fees become payable?
- How will you communicate with me during the application?
Mortgage Protection Should Be Part of the Conversation
Taking a mortgage creates a financial commitment that may continue for many years.
Protection planning asks a different question from mortgage advice: not simply whether you can afford the borrowing today, but what could happen to that affordability if illness, injury or death changed household income.
A protection adviser can discuss areas such as:
- life insurance;
- critical illness cover;
- income protection;
- mortgage-related protection;
- existing employer benefits;
- the level and duration of cover required.
The appropriate combination depends on income, mortgage balance, dependants, existing protection and budget.
Connect Experts’ protection guidance explains that advisers can assess mortgage commitments, income, dependants and existing cover before recommending suitable protection arrangements.
Protection should not simply be added automatically to a mortgage. Consider it based on the client’s actual financial risks and existing arrangements.
Higher-Value and More Complex Torphichen Properties
Torphichen’s recent transaction data shows that some larger detached homes can sit substantially above the wider West Lothian average.
Higher property values do not automatically make somebody a high-net-worth borrower.
However, larger mortgage requirements can become more specialist where applicants also have:
- significant bonus income;
- retained company profits;
- investment income;
- multiple businesses;
- complex remuneration;
- substantial assets but irregular income;
- several properties;
- large deposits derived from investments or asset sales.
In these cases, lender selection may depend less on a conventional income multiple and more on how each lender assesses the applicant’s complete financial position.
Equity Release and Later-Life Borrowing in West Lothian
For some older homeowners, the financial question shifts from how to buy a home to how existing property wealth fits into later-life planning.
Equity release is specialist borrowing and is not suitable for everyone.
A lifetime mortgage can allow eligible homeowners to release money secured against their home while retaining ownership, but interest may accumulate over time where repayments are not made. Existing secured borrowing usually needs to be addressed, and releasing equity can also reduce the estate available to beneficiaries and potentially affect entitlement to means-tested benefits.
Alternatives can include:
- downsizing;
- using savings;
- conventional residential borrowing;
- retirement interest-only mortgages;
- family assistance;
- borrowing a smaller amount;
- delaying expenditure.
Connect Lifetime has a dedicated West Lothian resource covering lifetime mortgages, drawdown, inheritance, alternatives and later-life considerations
Equity Release Advisers in West Lothian
This is the appropriate regional link rather than creating a Torphichen-specific equity-release claim where a dedicated Torphichen page is not available.
Search for a Mortgage Broker in Torphichen
The strongest mortgage decision is usually one that still makes sense after the headline rate attraction has passed.
Whether you are buying an older village property, moving home, remortgaging or dealing with more complex income, an experienced adviser can compare lender criteria alongside affordability and the property itself.
Use Connect Experts to search for a Mortgage Broker in Torphichen whose experience matches the problem you need to solve.




