
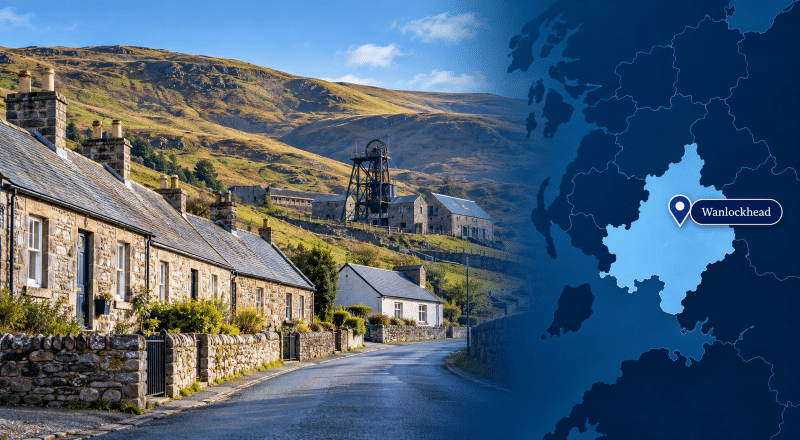
A Mortgage Broker in Wanlockhead can help borrowers look beyond the headline mortgage rate and consider whether the property, deposit, income and lender criteria fit together. In a village shaped by centuries of mining and a distinctive upland setting, buying a home reminds you that value is never determined by price alone; suitability matters just as much.
VisitScotland recognises Wanlockhead as Scotland’s highest village, and it retains a strong connection to its former lead-mining industry. Its housing and landscape differ from those in larger towns across Dumfries and Galloway.
That can make mortgage research more tailored to the property. An adviser can assess affordability, loan-to-value, construction, valuation concerns and lender criteria before recommending an appropriate route.
At a glance: Mortgage Broker in Wanlockhead
- Wanlockhead is an historic former lead-mining settlement in the Lowther Hills.
- It is recognised as Scotland’s highest village.
- Wanlockhead has been a designated conservation area since 1991.
- Traditional stone buildings and former miners’ housing contribute to its distinctive property stock.
- The average Dumfries and Galloway house price was £170,000 in July 2026.
- First-time buyers across Dumfries and Galloway paid £143,000 on average in July 2026.
- Wanlockhead addresses use the ML12 postcode area, an important geographical distinction even though the village is within Dumfries and Galloway.
- For unusual, older, or rural homes, relevant mortgage experience can matter more than an adviser’s physical distance.
Mortgage Advice in an Unusual Rural Housing Market
Wanlockhead does not have the volume or uniformity of housing found in a large urban market.
The council’s conservation review describes simple, functional buildings with stone elevations and slate roofs, alongside surviving features associated with the area’s historic mining industry. The council also identifies the settlement’s industrial origins and upland setting as central to its character.
For a mortgage applicant, those characteristics can make the individual property particularly important.
A lender may want to understand:
- the property’s age and construction;
- the condition of the roof, walls and other structural elements;
- whether alterations have been undertaken;
- the valuer’s assessment of marketability;
- access, services and other rural-property considerations;
- the requested loan-to-value;
- whether there is enough comparable evidence to support the valuation.
None of these points automatically makes a property unsuitable for a mortgage. They can, however, influence which lenders are comfortable with the security.
This is where a Mortgage Broker in Wanlockhead search should focus on experience and lender access, rather than simply the geographically closest adviser.
Wanlockhead Property Prices in a Wider Dumfries and Galloway Context
Local transaction volumes in a small village can be limited, so individual sales should not automatically be treated as evidence of another home’s value.
The Office for National Statistics provides a broader benchmark through its housing data for Dumfries and Galloway.
In July 2026, the provisional average property price across Dumfries and Galloway was £170,000, compared with £162,000 a year earlier. First-time buyers paid an average of £143,000, while homes bought with a mortgage averaged £166,000.
Property type also produced substantial differences:
- Detached: £260,000
- Semi-detached: £170,000
- Terraced: £137,000
- Flats and maisonettes: £88,000
These are local-authority averages rather than Wanlockhead valuations. That distinction matters. In a small rural market, a lender’s valuation of the actual property can carry considerably more weight than a county-wide average.
Historic Properties and Conservation Considerations
Wanlockhead’s conservation status provides another reason to investigate a property carefully before committing to a purchase.
Dumfries and Galloway Council records Wanlockhead as a conservation area and explains that conservation status can introduce additional controls over changes such as windows, doors, roofs, external finishes and certain extensions.
Buyers considering an older property should therefore establish whether previous alterations have the appropriate permissions and whether planned improvements could require further consent.
You can check current guidance through Dumfries and Galloway Council’s conservation-area information.
From a mortgage perspective, conservation status itself does not prevent borrowing. The more relevant questions are usually construction, condition, valuation, marketability and the lender’s individual property criteria.
A Mortgage Broker in Wanlockhead can compare these considerations with lender policy before an application is submitted.
First-Time Buyers in Wanlockhead
The area’s comparatively modest average house prices may attract first-time buyers, but purchase price is only one part of affordability.
Lenders normally assess:
- basic salary and additional income;
- employment history;
- self-employed accounts or tax evidence;
- deposit size;
- existing loans and credit commitments;
- dependants and household expenditure;
- credit history;
- mortgage term and age at the end of the term.
First-time buyers should also budget for valuation or survey costs, legal expenses, and the costs of maintaining the property after completion.
Scotland also has a different home-buying process from England and Wales, so buyers should understand both their mortgage position and the Scottish conveyancing process before making commitments.
Moving to Wanlockhead
Wanlockhead offers something fundamentally different from a conventional commuter suburb.
Its setting in the Lowther Hills, mining heritage, and relatively isolated position are central to the village’s character. VisitScotland describes it as Scotland’s highest village, while the council’s conservation assessment emphasises the relationship between its buildings, industrial remains and surrounding upland landscape.
For someone considering a move, the practical questions should therefore extend beyond the mortgage.
Consider:
- everyday travel requirements;
- access to employment;
- schooling and childcare arrangements;
- broadband and mobile connectivity at the specific property;
- winter access and exposure;
- property maintenance;
- local services;
- whether rural living suits the household over the longer term.
Mortgage decisions work best when the finance supports the way someone intends to live, rather than simply enabling the purchase.
Self-Employed and More Complex Mortgage Applications
A straightforward property does not always mean a straightforward applicant.
People living or buying around Wanlockhead may be employed, self-employed, contractors, company directors or receive income from several sources.
Different lenders can assess those incomes differently. A company director, for example, may encounter lenders using salary and dividends, while another lender may be prepared to examine salary plus a share of retained profits.
Applicants may also need specialist consideration where there is:
- recent self-employment;
- variable or seasonal income;
- overtime or bonuses;
- multiple employment;
- historic adverse credit;
- an existing property portfolio;
- gifted deposits;
- income continuing beyond conventional retirement ages.
Working with a Mortgage Broker in Wanlockhead can help identify lenders whose underwriting approach is better aligned with both the borrower and the property.
Why the Mortgage Valuation Matters
A lender valuation answers a specific question: whether the property provides acceptable security for the proposed mortgage.
That is not necessarily the same as establishing whether a buyer is paying the right price or whether the building will require repairs.
In a historic settlement with less uniform housing, comparable transactions may also be less plentiful than in a large development containing many similar properties.
A buyer may therefore decide that a more detailed property survey is appropriate alongside the lender’s valuation.
If the valuation is lower than the agreed purchase price, the resulting loan-to-value calculation can affect the mortgage. Borrowers may need to increase their deposit, renegotiate the price or consider another approach depending on the circumstances.
Mortgage Protection Should Be Part of the Conversation
Arranging a mortgage creates a long-term financial commitment. It is therefore sensible to consider what happens if the household’s circumstances change after completion.
Protection can include products designed to provide financial support following death, serious illness or an extended inability to work, depending on the policy selected and its terms.
Borrowers who want to assess the risks alongside their mortgage can search for specialist protection mortgage brokers.
The objective is not simply to insure a loan. It is to consider whether the household could continue meeting important financial commitments if an income unexpectedly disappeared.
Later-Life Borrowing and Equity Release
Older homeowners may have different objectives. Rather than buying their first property, they may want to restructure existing borrowing, release capital, or understand whether staying in their home is financially practical.
Options depend on age, property value, existing borrowing, income and longer-term objectives.
Where equity release is being considered, specialist regulated advice matters because releasing equity can affect an estate’s value and may affect entitlement to means-tested benefits.
Homeowners can explore specialist support from equity release advisers in Dumfriesshire.
Does Your Adviser Need to Be Based in Wanlockhead?
Not necessarily.
Mortgage advice is increasingly provided by telephone and video, and lender research depends on the applicant’s circumstances and the property rather than the physical distance between borrower and adviser.
For distinctive rural homes, specialist knowledge of property criteria, underwriting and lender appetite may be more valuable than sharing the same postcode.
Someone searching for a Mortgage Broker in Wanlockhead can therefore consider advisers from a wider geographical area while still looking for relevant experience.
The Connect Experts mortgage adviser directory helps borrowers compare advisers based on their circumstances and mortgage requirements.
Start Your Mortgage Search in Wanlockhead
A mortgage is ultimately an agreement between three realities: what the buyer can afford, what the lender is prepared to accept and whether the property represents suitable security.
Wanlockhead’s historic housing, conservation status and distinctive rural setting make that relationship especially important.
If you are buying, moving, remortgaging or reviewing an existing mortgage, searching for a Mortgage Broker in Wanlockhead through Connect Experts can help you identify an adviser whose experience matches both your circumstances and the property you are considering.
Find a mortgage adviser suited to your circumstances.




